DEADLINES AND PUBLIC PROCESS
Get my comprehensive parcel analysis
Look up your parcel by address, map/lot or name, then choose “Comprehensive analysis (printable).” A comprehensive analysis and comparison of public records; information only.
This page lists dates and public processes as published by Maine Revenue Services (MRS) and Maine statute. It does not say whether any owner should file anything or what any filing should contain.
1. Dates
The firm’s page gives the commitment date as 1 October 2026. Under 36 M.R.S. §841 an abatement application must be filed with the assessor within 185 days of commitment, which from 1 October 2026 is 4 April 2027. The marker below moves with today’s date. The first tax payment is due 15 November 2026.
2. The abatement timeline, as the State and the statutes describe it
Whether to file, what to claim, and how to present it are decisions for each owner, with a Maine attorney or MRS if the owner wants advice. This website does not advise on them.
3. The budget
A revaluation changes who pays what share of the levy. It does not by itself change the amount the Town raises. The amount raised is the levy, and the levy is the budget. As the Town describes it, the Town Manager drafts the budget, the Budget Committee reviews it, the Select Board makes a recommendation, and voters decide at the June town meeting. Dividing any budget change by the Town’s taxable value gives the change in the rate; multiplying the rate by a property’s value gives its bill.
4. Public meetings and processes
After commitment: what happened
On 3 September the Select Board voted 4–1 to go forward with the new values after seventeen residents spoke against them. On 17 September ten more spoke; the Town Manager said on the record that the $392,175 revaluation contract “didn’t go out to bid” and was a sole-source award. On 29 September, after an hour in executive session with a tax attorney, the Board read a statement that it “does not have the legal authority to interfere with the assessor’s valuation determination” and took no vote. On 1 October, asked who commits the taxes, the Town Manager said: “The tax assessor is the only one that’s allowed to commit taxes.” The assessor, who is also the president of the company that produced the values, committed the roll; the firm’s own page gives the commitment date as 1 October, the same evening. The committed values appeared on that page on 6 October: 831 parcels differ from the roll the public saw in September, and $39.9 million came off, with no notice to any owner. Every parcel page on this site now shows both figures and marks the changed ones.
Across the three meetings, 25 different residents and property owners spoke against the revaluation or the process, 37 speaking turns in all. No member of the public spoke in favor.
The statutory timeline
Maine statute and MRS Bulletin No. 10 set the following dates for an abatement of property taxes: an application is filed with the assessor within 185 days of commitment, which from 1 October 2026 is 4 April 2027 (36 M.R.S. §841). If the assessor does not answer in 60 days, the application is deemed denied (§842). An appeal to the Board of Assessment Review is due within 60 days (§843), and a further appeal to Superior Court within 30 days of that board’s decision (Rule 80B). This is information only. It does not say whether any owner should file. See Deadlines & public process.
What has been filed
A formal complaint to Maine Revenue Services and the Attorney General on the sales-ratio study, the land and card records, the sole-source contract and the assessor’s unanswered records requests; a Freedom of Access Act matter now with the State’s Public Access Ombudsman; and requests for the 2026 commitment book, the warrant and the tax rate calculation form, which the Town has acknowledged and not yet produced. A recall petition is circulating.
ABOUT THE REVALUATION
Norway’s 2026 revaluation was carried out by John E. O’Donnell & Associates, a private firm hired by the Town through the Select Board. By the firm’s own description it was an exterior visual review and measurement of each property, not a full appraisal.
Under Maine law the municipal assessor determines the assessed value of each property, and the assessor’s duties are set by statute and by MRS rules. This website does not interpret those duties for any particular property.
This site lets a reader look up a parcel’s public record card, see how the 2025, proposed 2026 and committed 2026 figures compare, and see how the card compares with others in town. What an owner shares, files or says to the Town is the owner’s own decision. For questions about legal rights or procedure, a Maine attorney or Maine Revenue Services can answer them.
Information only. Not legal advice. This website offers no advice on whether to file anything or what any form should contain.
What this is, and how to use it
Norway Parcel Review takes the 2026 property record cards prepared by the Town’s revaluation contractor, John E. O’Donnell & Associates, and reads every one of them against the Town’s prior tax commitments and the sales that have actually occurred in town. It is written for residents, not assessors: it explains what the numbers on your card mean, where they came from, and how they compare with the State’s standard. It is prepared by a Norway property owner from public records. It is not an appraisal, not legal advice, and not a Town publication. Why these records are public, and what this initiative stands for, is set out under Purpose & sources.
To review your parcel, type your street address, your map/lot number (it is on your tax bill), or your name into the box above and choose your account. You will get a review in six parts: the headline numbers (value and tax, 2025 against 2026); where the card stands against its class, its street, the sales in this site’s own ratio analysis, and its purchase history; the card itself, line by line; the closest sales of similar property; every account on your street; and how to act, with deadlines. The Print button makes a copy to keep or to attach to an abatement application, and the address in your browser bar can be sent to a neighbor so they see the same review.
Two things the data cannot see. The price on a card is what the Town recorded on the deed; when several parcels were bought together, the same total appears on each of them, and the review says so and compares the combined assessment instead. And a card cannot tell whether a building was rebuilt after it was bought, so where a purchase looks far below today’s assessment the review also gives the building’s standing against every structure of its type in town — that comparison, not the old price, is the test for a house that has been renovated. If your review gets something wrong, the correction is welcome; the data behind every line is public and can be re-checked.
To understand the whole town, use the tabs above — Town-wide findings, the Condition & obsolescence guide, Relief programs, Sources. In brief: what the revaluation did in total, the staircase (bills rose most where homes were worth least), who carries the increase by class and by lake, what this site’s own sales analysis shows, how the values were made, the budget and where it is heading, and the relief programs that exist now with links to apply. Every figure on this site is computed from the published cards and rolls and can be checked against them.
WHAT IS MILL RATE?
A mill rate is the price tag the Town puts on every $1,000 of your property’s assessed value. “Mill” is an old word for one-tenth of a cent. One mill equals $1 of tax for every $1,000 of value. If the mill rate is 10.96, you owe $10.96 for every $1,000 your property is assessed at.
Example: $300,000 assessed ÷ 1,000 × 10.96 = $3,288 a year
The Town sets one mill rate for the whole town, and it works like this: the Select Board decides how much money the Town needs to raise for the year (the levy). That total gets divided by the assessed value of every taxable property in town, added together. The number that comes out is the mill rate. Every single property owner is charged that same rate — nobody gets a special number because of who they are. The rate itself is completely fair. The problem is what it gets multiplied against: the assessed value.
Why one fair rate can still produce an unfair bill
The mill rate only works fairly if every property’s assessed value is an honest match for what it is actually worth. If a house is assessed too high, its owner is charged the mill rate against a bigger number than the real value — so they pay more tax than their fair share. If a house is assessed too low, its owner is charged the same mill rate against a smaller number than the real value — so they pay less than their fair share, and everyone else in town quietly makes up the difference. The rate never changes. The unfairness lives entirely inside the assessed value, not the rate.
This cuts both ways, and it does not care whether a property is expensive or modest. A mobile home valued too high and a lakefront cottage valued too high are overpaying for the exact same reason. A modest house valued too low and a waterfront estate valued too low are underpaying for the exact same reason. The only thing that decides who wins and who loses is whether the card got the value right — not the mill rate, and not what kind of property it is.
House A, a modest home, is really worth $150,000, but its card values it at $180,000 — 20% too high. At a 10.96 mill rate it is billed $1,972.80, versus $1,644.00 if the card had been right. House A pays $328.80 a year more than its fair share, every year, until someone corrects the card.
House B, a waterfront home, is really worth $600,000, but its card values it at $500,000 — about 17% too low. At the same 10.96 mill rate it is billed $5,480.00, versus $6,576.00 if the card had been right. House B pays $1,096.00 a year less than its fair share — and that missing $1,096 does not disappear. It has to come from somewhere, and it comes from every other taxpayer in town, House A included.
Why this means people pay a different real tax rate, even at one mill rate
Two homes worth the same amount should pay the same tax. When their assessments are wrong by different amounts, they do not. Divide each bill by what the home is actually worth, and you get that owner’s real tax rate — the true percentage of their property’s value they are paying, as opposed to the percentage of their assessed value. House A above pays a real rate of about 1.32% of its true worth ($1,972.80 ÷ $150,000). House B pays a real rate of about 0.91% of its true worth ($5,480 ÷ $600,000). Both are billed at the identical 10.96 mill rate on paper. Neither one is actually paying that rate in real life — and the 0.40-percentage-point gap between them is the whole problem with a town-wide mill rate: it can only ever be as fair as the values it gets multiplied against. Get the values right, for every parcel and every class of property alike, and the same one mill rate becomes fair for everyone it touches.
This is why a wrong card is never a small, private mistake. Every dollar an undervalued property escapes paying is a dollar the Town still needs, and it comes out of every correctly — or over — valued property’s bill instead. See Winners & losers and Waterfront burden for what this looks like in Norway’s own 2026 numbers, and the Condition & obsolescence guide for what the standard says each factor means and how the 2026 cards record it.
WHAT ARE CONDITION & OBSOLESCENCE?
Every building on the 2026 roll starts as a brand-new replacement cost — what it would cost to build that exact structure today — and then gets marked down by three separate judgment calls. Condition asks how worn out it is. Functional obsolescence asks whether something about its own design makes it worth less, no matter how well it is kept up. Economic obsolescence asks whether something outside the property line — something the owner cannot fix — is dragging its value down. None of the three change what the building physically is. All three change what a real buyer would actually pay for it.
Norway’s 2026 revaluation was an exterior assessment: the fieldwork was observation and measurement of each building’s outside footprint, backed by photographs, not a walk-through of the inside. That matters here specifically, because two of these three judgment calls — condition and functional obsolescence — are largely about what a house is like inside: a worn kitchen, a failing furnace, an awkward floor plan, a bathroom that was never finished. None of that was seen firsthand on this pass. It was inferred from the outside and applied anyway.
Example: $300,000 new × 85% condition × 100% functional × 100% economic = $255,000
1. Condition — how worn out it is
Condition is physical wear: an old roof, worn floors, a furnace due for replacement — the stuff that comes with age and use on any building, however well it was built. It is written as a percentage of “like new.”
An exterior visit can genuinely see quite a lot, if it looks: a foundation that has visibly cracked, shifted or settled; original single-pane wood windows, especially where the glazing has failed or a pane is cracked; a porch, deck or set of steps with rotted, sagging or missing boards; a roof with curling, missing or moss-covered shingles, or a visible sag in the roofline; siding that is missing, rotted, or has gone years without paint. Each of these can be seen from the street, which is what an exterior-only review looks at.
16 King Street: a 936 sq ft one-story house rated 60% — the lowest condition rating used anywhere on the 2026 roll, and a floor no card goes below no matter how bad the building actually is. This one is visibly structurally unsound from the street — exactly the kind of defect an exterior-only visit is supposed to catch — and 60% is as far down as the rating goes regardless. What the exterior alone could not have priced in: this property’s own listing additionally discloses no running water or heat at all, and it is under contract as a tear-down at $60,000 — interior facts no drive-by could ever have found. The card still carries the building at $76,080 and the full parcel at $168,221. For comparison, PT103’s scale (p. 81) lists “Poor” at 50% and “Unserviceable” below 50%; the card carries this building at 60%.
47 Elm Street: an ordinary 1967 one-story house, 1,040 sq ft, rated 85% — normal wear for its age, nothing alarming from the curb. Building value $166,805; full parcel $268,265. This is the single most common condition rating on the entire 2026 roll: 3,025 of Norway’s 11,552 building rows — more than one in four — are rated exactly 85%. A house like this is the roll’s definition of “normal.”
2. Functional obsolescence — a flaw built in
Functional obsolescence is a markdown for something about the building’s own design that the market discounts regardless of maintenance: an outbuilding too large for what the lot can use, a layout nobody would build today, one bathroom for a house with four bedrooms.
688 Crockett Ridge Road: a 3,240 sq ft barn, a 1,560 sq ft garage and a 1,984 sq ft carport all carry a 70% functional factor — a marked-down 30% of their replacement cost, because a house parcel has no real use for that much barn space. It is one of only nine of Norway’s 205 barns to get this treatment. This factor is rare townwide: only 794 of 11,552 building rows carry any functional markdown at all, and almost all of it sits on outbuildings like this one or on already-derelict main houses — not on the ordinary living space of an occupied home.
3. Economic (external) obsolescence — a problem next door
Economic obsolescence is a markdown for something outside the property line that the owner cannot fix: a derelict building next door, a busy highway, a block that has gone visibly blighted. It is supposed to apply evenly to every property exposed to the same condition — not to some of them and not others.
King Street is eight parcels long. One has vanished outright: 7 King Street was a home; it was demolished, and the lot now sits paved over as a parking area — carried on the card simply as vacant land, with no building on it at all. Two more parcels carry four derelict or unused structures between them: 12 King Street, a vacant former light-industrial warehouse; and 14 King Street, whose home and detached garage are both visibly structurally unsound and both rated at the town’s 60% condition floor — the garage’s doors are broken and failing, and mature trees are growing against the foundation, heaving it, while the house carries an 80% functional markdown and the garage a 90% functional markdown. 16 King Street, also visibly structurally unsound, is the derelict tear-down above, with no water or heat, at the same 60% floor. Of these four structures, only the warehouse at 12 King Street carries any economic obsolescence factor at all (90%) — neither building at 14 King Street does, and neither does 16 King Street. The remaining four parcels on the same short street — 8, 9, 13 and 15 King Street — are all occupied multi-family rental buildings, carded at 100%, with no economic markdown of any kind.
Can an owner really charge full market rent for occupied apartments on a street where one home was bulldozed for a parking lot and three more buildings sit derelict or vacant? On this street the card records a 90% economic factor on the warehouse at 12 King Street and 100% on the occupied buildings beside it.
A 100% rating is not a finding that nothing is wrong — it is just the assessor’s starting position, and it is not the final word. MRS Bulletin No. 10 states that the taxpayer carries the burden of proof in an abatement (36 M.R.S. §841). A 90% economic factor appears on 12 King Street and 100% on the occupied buildings beside it. This site does not say what any owner should do about that.
See the Condition & obsolescence guide for the full technical breakdown of every factor townwide, the professional standards behind each one.
What the revaluation did
The revaluation more than doubled the town’s taxable value and cut the mil rate nearly in half. A doubled value at a halved rate would leave every bill where it was; what actually moved bills is that values did not double evenly. The figures below are computed from all 3,514 accounts on the 2026 roll against the 2025 commitment. Tax for 2026 is calculated at the proposed rate with each parcel’s 2026 exemptions; the 2025 tax is the amount actually billed.
The less your home was worth, the more your bill went up
Homes only (houses, mobile homes, multi-family), grouped by what they were assessed at on the 2025 roll after exemptions. Bars show the median change in the tax bill; the figure beneath is the share of bills that rose.
Homes are sorted into these bands by their 2025 net taxable value — after that parcel’s own 2025 exemptions. Sorting instead by the pre-exemption land-plus-building total moves 315 of the 2,479 homes here (12.7%) into a different band, since exemption amounts vary by owner. The staircase shape holds either way, but the exact figures shift a little at the low end: the under-$100,000 band’s median bill change is +48.4% sorted the way it is above (by net value) versus +53.7% sorted by gross value. Every other band moves by less than 4 percentage points.
Who carries the increase
The same levy, distributed differently. “Value change” is the median parcel’s assessed value; “tax change” is the class total at 10.96 mils against what the class paid in 2025.
The lakes did not move together
The sales ratio study, by sub-class
Information only. This section describes public records: the Sales Ratio Analysis the Town produced from John E. O’Donnell & Associates, the property types the State’s transfer-tax declaration (RETTD) website uses, and a State rule. It is not legal advice and does not say what any owner should do. It is separate from the sales test further down this page, which uses sales this site gathered itself.
What the study is
Sales Ratio Analysis, Norway Reval, run August 22, 2026: 87 sales, filtered to “BuildingValue > 0 AND Sale Date between 1/1/2025 and 12/31/2026.” Total assessed value $36,659,787 against total selling price $36,741,528. Median ratio 1.00; coefficient of dispersion 4.5 (computed from the printed ratios). The report prints a class on 73 of the 87 sales and leaves the class blank on 14. The three class names it prints are Rural Residential (nonwaterfront), Waterfront and Commercial and Industrial.
Statistics calculated from the study’s own printed ratios
Computed on this page’s sub-classes from the 87 ratios printed in the Town’s report. Median is the middle ratio. Weighted mean is total assessed value divided by total selling price. COD (coefficient of dispersion) is the average absolute distance of the ratios from the median, as a percent of the median. PRD (price-related differential) is the mean ratio divided by the weighted mean.
| Group | Median | Mean | Weighted mean | COD | PRD |
|---|---|---|---|---|---|
| All 87 sales | 1.000 | 0.999 | 0.998 | 4.48 | 1.002 |
| Houses, not on the water (n=60) | 1.010 | 1.009 | 1.009 | 4.11 | 1.000 |
| Waterfront houses and camps (n=11) | 1.010 | 0.994 | 0.979 | 5.58 | 1.015 |
| Mobile / manufactured homes (n=10) | 0.970 | 0.943 | 0.945 | 5.26 | 0.997 |
| Multi-family, 2–4 units (n=1) | 1.020 | one sale: no dispersion statistics | |||
| Multi-family, 5 or more units (n=2) | 1.010 | 1.010 | 1.020 | 1.98 | 0.990 |
| Commercial, industrial and institutional (n=1) | 0.970 | one sale: no dispersion statistics | |||
| Outbuilding only (n=2) | 1.010 | 1.010 | 1.018 | 1.98 | 0.992 |
The published reference ranges. IAAO Standard on Ratio Studies (2013), Table 1-3, as cited in this site’s earlier review: median ratio 0.90 to 1.10; PRD 0.98 to 1.03; COD 5.0 to 10.0 for newer, more homogeneous single-family areas, 5.0 to 15.0 for older, more heterogeneous areas, and 5.0 to 20.0 for rural, seasonal or recreational areas. The table’s note reads that CODs lower than 5.0 may indicate sales chasing or non-representative samples. Check the current IAAO edition for the exact wording. Small classes (fewer than 8 sales) give unstable dispersion figures.
What the State’s own rule says about classes and sample size
- A segregated ratio study (one class of property) needs a minimum of eight samples within each class.
- When the sales in both the base period and the expanded period fall short, the minimum is reached by combining the available sales with appraisals conducted by the State bureau using the State assessment manual (Section 3(D); a “sample” may include such appraisals, Section 1).
- Classes are studied separately when the sales do not reasonably reflect the class mix, or when average ratios among classes differ by more than ten percentage points. The rule’s own examples of residential classes are nonwaterfront, waterfront and condominium (Section 4).
This is an administrative rule for how the State Tax Assessor builds the State Valuation. It is not a statute, and it does not by its terms bind a town’s revaluation contractor. It is shown here as the State’s own benchmark for what “enough samples in a class” means. The study the Town produced lists sales only; it lists no appraisals.
Sub-classes compared: the firm’s study, the roll, and the State’s RETTD types
Each Norway parcel is placed in one sub-class using the same rule for the roll and for the 87 sales (waterfront means a lake or pond frontage line on the card; multi-family 5 or more units follows RETTD’s “Commercial – 5+ Unit Apartment”). “Roll” is parcels on the 2026 roll. “Study” is sales in the firm’s study. “RETTD” counts Norway transfer-tax declarations from January 2025 on, by the property type the parties reported; 20 more have no type. Percentages are shares of the roll and of the study.
| Sub-class (this page) | Class the firm’s study prints | RETTD property type | Roll parcels | Sales in the study | Study median ratio | RETTD declarations | Against the State’s eight-sample benchmark |
|---|---|---|---|---|---|---|---|
| Houses, not on the water | Rural Residential (nonwaterfront) | Residential – Rural / Urban / Other | 1,489 42.4% | 60 69.0% | 1.01 | 242 | Meets the benchmark |
| Waterfront houses and camps | Waterfront | Residential – Lake/Pond Front | 419 11.9% | 11 12.6% | 1.01 | 38 | Meets the benchmark |
| Mobile / manufactured homes | (no separate class printed) | Residential – Mobile Home | 518 14.7% | 10 11.5% | 0.97 | 5 | Meets the benchmark |
| Multi-family, 2–4 units | (no separate class printed) | Residential – 2-4 Unit Apartment | 70 2.0% | 1 1.1% | 1.02 | 7 | Below the benchmark (7 short) |
| Multi-family, 5 or more units | (no separate class printed) | Commercial – 5+ Unit Apartment | 24 0.7% | 2 2.3% | 1.01 | 4 | Below the benchmark (6 short) |
| Commercial, industrial and institutional | Commercial and Industrial | Commercial / Industrial / Misc Codes | 177 5.0% | 1 1.1% | 0.97 | 15 | Below the benchmark (7 short) |
| Vacant land | (excluded: building value must be above $0) | Vacant Land – Rural / Urban / Other | 644 18.3% | 0 0.0% | – | 56 | No sales in the study |
| Vacant waterfront land | (excluded: building value must be above $0) | Vacant Land – Lake/Pond Front | 63 1.8% | 0 0.0% | – | 2 | No sales in the study |
| Outbuilding only | (no separate class printed) | (no separate RETTD type) | 110 3.1% | 2 2.3% | 1.01 | 0 | Below the benchmark (6 short) |
The firm’s printed “Commercial and Industrial” class holds two sales; this page places one of them (a ten-unit building) in multi-family 5+ units. The firm printed “Waterfront” on ten sales and left an eleventh waterfront sale blank.
Observations
- Three sub-classes meet the eight-sample benchmark in the firm’s study: houses not on the water (60), waterfront (11) and mobile / manufactured homes (10).
- Six do not: multi-family 2–4 units (1), multi-family 5+ units (2), commercial (1), outbuilding only (2), vacant land (0) and vacant waterfront land (0). Together these are 1,088 of 3,514 roll parcels (31%).
- The study’s own filter, building value above $0, excludes vacant land by design. Vacant land is 707 roll parcels (20%).
- Among the sub-classes with sales, the study’s class medians run from 0.97 to 1.02, a spread under the rule’s ten-point trigger for separate studies.
- RETTD declarations are far more numerous than the study’s sales (369 typed declarations against 87 sales). They include family transfers, partial interests and other transfers that do not reflect market value; RETTD does not show whether a transfer was arm’s-length, and property type and map/lot are reported by the parties themselves.
The property types the State’s RETTD site offers (what a declaration can be filed as)
Residential: 2-4 Unit Apartment; Lake/Pond Front; Mobile Home; Oceanfront; Other; Rural; Stream/Riverfront; Urban.
Vacant Land: Agricultural; Commercial Zone; Lake/Pond Front; Oceanfront; Other; Rural; Stream/Riverfront; Urban.
Commercial: 5+ Unit Apartment; Automotive; Bank; Hotel/Motel/Inn; Marina; Medical; Mixed Use; Nursing Home; Office; Other; Restaurant; Retail; Shopping Mall; Warehouse.
Industrial: Gas and Oil; Gravel Pit; Heavy Manufacture; Light Manufacture; Lumber/Saw Mill; Other; Pulp/Paper Mill; Utility.
Misc Codes: Airport; Condominium; Conservation; Current Use Classification; Government; Mobile Home Park; Nonprofit; Other; Timeshare Unit.
Sources: Town of Norway, Sales Ratio Analysis, Norway Reval (O’Donnell, run 22 Aug 2026); Maine Tax Portal, RETTD Public Lookup (property-type list and Norway declarations, saved September–October 2026); Maine Revenue Services, Rule Chapter 201 (maine.gov/revenue/rules). Each parcel’s sub-class and its count appear on its own parcel review.
The firm’s CMAs have stated on the record
These are statements of opinion and description made by the firm’s principal and its assessing staff (the firm’s staff hold Certified Maine Assessor designations, per Mr. O’Donnell’s Sept. 3 statement). They are reproduced word for word from machine-generated transcripts, with omissions marked [...]. They are published so the public can read how the firm describes its own method. This page draws no conclusion from them.
Reproduced word for word from transcripts, with timestamps. Short excerpts can omit context. The firm and its staff are invited to send a correction, clarification or reply to glatzcorp@gmail.com, and it will be posted beside the quote.
“Assessing and assessed values are not precise, independent fee appraisals. [...] Yes, we want our values to be as close to market value for every single property that we possibly can. But again, we cannot offer perfection on that.”
John O'Donnell, principal — Sept. 3 Select Board meeting, 00:10:58
“But if you have a range of 50% to 150%, and that is what your tax distribution is based on, you are not distributing taxes fairly. That's a pretty good description of Norway's prior assessments through 2025.”
John O'Donnell, principal — Sept. 3 Select Board meeting, 00:04:41
“The market has changed at different rates for different properties. And part of our job is is to try to maintain—again, to go back to equal distribution of the tax burden by trying to get properties within reasonable proximity of each other.”
John O'Donnell, principal — Sept. 3 Select Board meeting, 00:12:32
“We—we see so few deeds for mobile homes. I—I have no idea. I'm not sure what that would tell us about what they go for on the open market. What we can say is the bill of sales that we see are, in effect, the— the basis for the new numbers that we have on mobile homes.”
John O'Donnell, principal — Sept. 3 Select Board meeting, 00:49:07
“And six of us do certified main assessor designations, done this for 20, 30, 40 years.”
John O'Donnell, principal — Sept. 3 Select Board meeting, 00:26:53
“I am now busy working on the stuff he put forward. And I—at first, I just did some studies to test it. And then I found he's got some merit. Like, I don't agree with everything he did, but he— he brought enough forward so that I have a list now of things that I have to do.”
Mike O'Donnell, firm assessing staff — Sept. 3 Select Board meeting, 00:59:09
“we generally start with the 3. Now, if we get to a section of town that we think is particularly distressed for one reason or another, or less desirable. [...] Then we might find another spot that maybe it's a later subdivision, a little bit nicer, kind of got some integrity to it, buildings are all around the same time. We find that— we think that might be a little bit more desirable. We might assign that one a 4.”
Mike O'Donnell, firm assessing staff — Sept. 1 review session, 00:03:42 and 00:04:13
“So if you are just dealing with wear and tear, weathering, depreciation over time, that's condition. If you're dealing with something that's unfinished, you know, in process of renovation, then you would have a discount due to functional obsolescence.”
Mike O'Donnell, firm assessing staff — Sept. 1 review session, 00:36:38
“Now, every once in a while, we're a little loose with those, but mostly they follow that pattern.”
Mike O'Donnell, firm assessing staff — Sept. 1 review session, 00:37:11
“So your point that we are meaningfully overvaluing low-value property, creating an inflated total value, that has merit. This one where it wasn't already happening in the school funding formula, that does not have merit.”
Mike O'Donnell, firm assessing staff — Sept. 1 review session, 00:59:49
“One, I'm definitely changing that. Two, I'm probably going to change your neighborhood simply because I think like maybe you're right and maybe every decent duplex is surrounded by what you're surrounded by.”
Mike O'Donnell, firm assessing staff — Sept. 1 review session, 01:10:37
What the sales say: this site’s own sales test (separate from the firm’s study above)
Three dials, no schedule
Every building value on the 2026 roll is a cost table multiplied by three judgments made from the driveway: a grade (1.00 to 10.00), a condition (0–100%), and two obsolescence factors. Land is a numbered table (1–10) with a first-acre price from $30,600 to $300,000, a per-acre curve for the rest, a per-foot price for shore frontage, and a flat “site improvement” charge ($35,000 on 1,980 parcels). At the September 1 hearing the assessors’ agent was unable to produce a written definition of any table, the grade and condition guide, or the obsolescence schedule. That is not a complaint about any one card; it is why no owner can check their own.
- Condition has a floor at 60%. 230 building rows sit at exactly 60% and 72 below it, in a town whose derelict structures are carded at $168,000–$204,000. The eight low-condition sales in the study sold above the town median ratio, all eight.
- The two obsolescence factors point in different directions. 92.5% of building rows carry no markdown of either kind. Where a factor is applied, it splits by type: the functional factor lands mostly on homes — 623 of its 794 marked rows are frame houses or mobile/manufactured homes, only 48 are commercial — while the economic/external factor runs commercial, 84 of its 102 marked rows (82%) discounted at exactly 90% for “commercial/institutional/other” use. Only five parcels in the whole town carry any economic markdown at all.
- The land schedule was set to house sales, not land sales. Seven bare lake lots sold since 2021 at 50–80% of their 2026 land assessment; large woodland tracts sold at $1,200–$1,800 an acre against $2,200–$3,900 on the roll.
- Older cottages were priced as new houses. On North Pond a 1970s cottage and a 2024 build on the same lot sit within about $100,000 of each other on the roll; the sales put them $350,000–$500,000 apart. The cottage sales were removed from the study as “non-market.”
The budget: what the Town raises, and where it is heading
A revaluation decides shares; the levy — the amount the Town raises by property tax after other revenues — decides the total. Norway’s levy went from $7,478,397 on the 2022 roll to $11,458,048 on the 2025 roll, 15.3% a year, against consumer inflation of about 3.4% a year and growth in taxable parcels of 2.0% a year. The figure given by the assessors’ agent for 2026 is $12,936,375, +12.9% in one year (it was described at the hearing as “about 8%”). At that pace a bill doubles every 4.9 years whatever the roll says.
2026 net taxable $1,193,348,401 × 9.6016 mils = $11,458,048 (the same levy: the “levy-neutral” rate)
2026 net taxable $1,193,348,401 × 10.96 mils = $13,079,098 (proposed: +14.1%, the 2026 figure plus $142,723 overlay)
2025 net taxable $559,894,030 × 23.11 mils = $12,936,375 (the 2026 figure raised on the old roll)
Where it’s been: sixteen years of tax commitments, 2009–2026
Every point through 2024 is Norway’s own line in Maine Revenue Services’ annual Municipal Valuation Return Statistical Summary — the state’s independent record of what each town actually committed, not this office’s calculation. The dashed segment marks the gap where no state summary was available (2025) and the 2026 figure, which is the proposed commitment pending the Board’s final rate.
Ten years out, four arithmetic paths
Compound arithmetic from the 2026 figure; not a forecast. Per-parcel figures divide the levy by a parcel count growing 2.0% a year.
The bottom two paths are not austerity; they are what a town this size grows at. The gap between them and the top two is the Board’s choice, made one budget at a time, and no revaluation, ratio, or abatement changes it by a dollar. Whatever the Board decides about the roll, it should publish the levy, the levy-neutral rate, and this chart beside any mil rate it proposes.
Vacant and derelict buildings shift the levy onto everyone else
Because the property tax must track market value (Me. Const. Art. IX, §8), a deteriorating building is a valuation discount — a lower assessment, a smaller share of the levy, and the difference made up by every other bill in town. Reading the 2026 cards against the 2025 roll, 72 improved parcels had their building value frozen or written down against a town-wide median building increase of 1.78× (78%); 44 of those 72 were written down in absolute dollars. Bringing those 72 buildings only to the town’s own median factor would add roughly $8.3 million of taxable value — about $91,000 a year at 10.96 mils, paid today by every other taxpayer. The pattern is visible bill by bill: the 72 candidate parcels carry a median tax decrease of 16.2% while the median improved parcel in town rose 10.6%, and three in four of them are going down while their neighbors go up.
A citizen proposal — a vacant & derelict building registration ordinance modeled on Bangor, Maine’s Chapter 223 — would put an escalating fee on buildings left vacant and unsecured, funding code enforcement rather than raising anyone’s assessment, and giving owners of neglected property a real reason to repair, sell, or demolish rather than warehouse. It does not touch the constitution’s market-value rule; it sits beside the tax system as a regulatory fee, the same tool Bangor and a growing number of Maine towns already use.
Articles
Longer pieces from this project on the 2026 revaluation and the rules around it, written for Norway residents and cited to the statutes, manual pages, and public records they draw on. Newest first. Each opens as a standalone PDF you can read, print, or pass along.
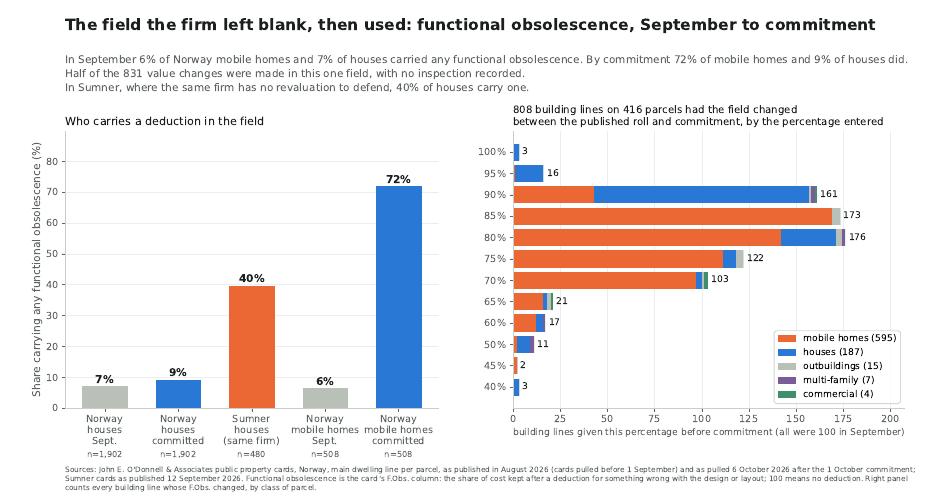
The field the firm left blank, then used: functional obsolescence before and after commitment
Functional obsolescence is the card’s deduction for something wrong with a building’s design or layout. On the September roll the firm left it at 100 (no deduction) on 93% of Norway houses and 94% of mobile homes, where its own Sumner cards use it on 40% of houses. Between the September roll and the 1 October commitment it changed the field on 416 parcels, 808 building lines, most of them mobile homes in Town & Country, with the visit history showing a desk “Reval Review” and no inspection. By commitment 72% of mobile homes carried a deduction. Half of the 831 value changes made after the public saw the roll were made in this one field.
Read the article · Download · Norway_Functional_Obsolescence_Before_After.pdf
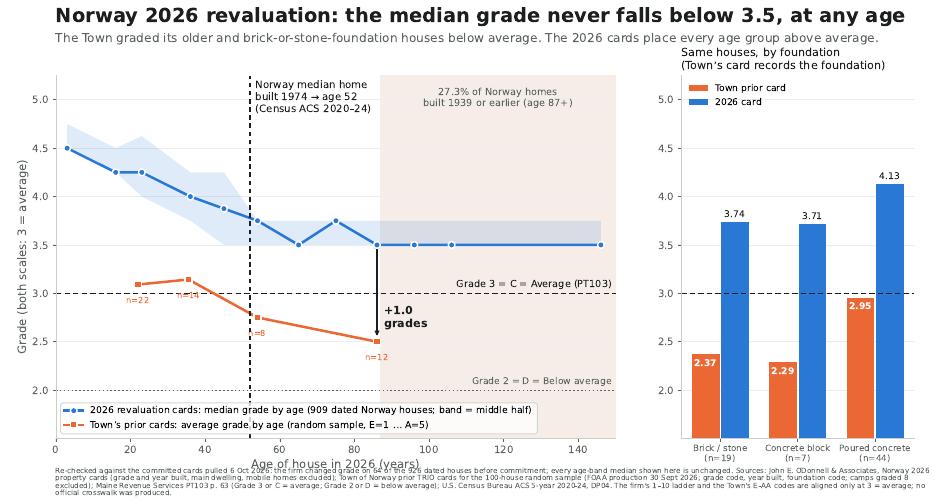
Grade against age: the 2026 cards never grade a house below 3.5, at any age
Building grade is how well a house was built. On the 2026 revaluation cards the median grade of 909 dated Norway houses never drops below 3.5 in any age band, including the 27% of Norway homes built before 1940. The Town’s own prior cards, read for the 100-house random sample, carry the brick, stone and block-foundation houses at 2.3–2.4 on the old scale; the 2026 cards put the same houses near 3.7. The firm has published no written definition of its 2.00–10.00 grade scale and no crosswalk to PT103’s five grade levels, so what any firm grade equals on the State’s scale is UNKNOWN. Note: this PDF draws a reference to PT103’s scale; that is the State’s scale, not a measured equivalent of the firm’s numbers.
Read the article · Download · Norway_Grade_vs_Age_PT103.pdf
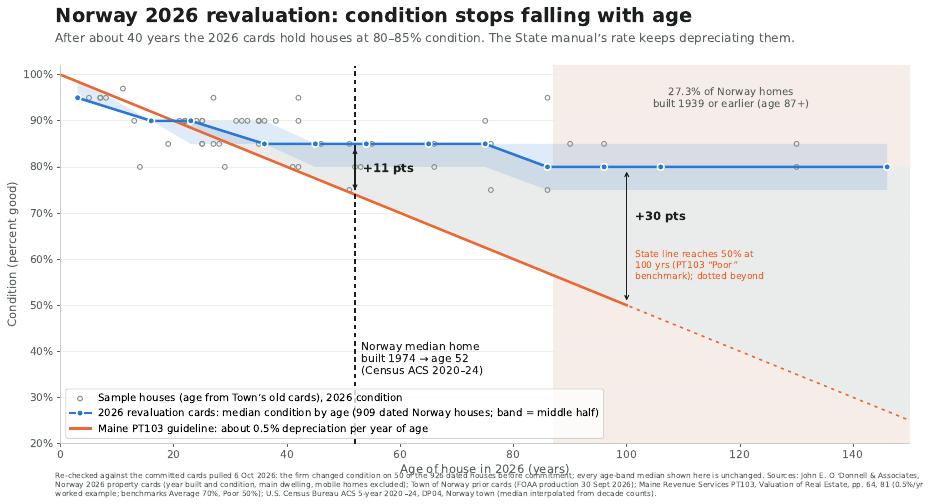
Condition against age: the 2026 cards stop depreciating at about 40 years
Condition is the share of a building’s cost left after wear. PT103 (p. 64) uses about one-half percent a year as its guideline, which puts a 45-year-old house near 77% and a century house near 50%. On the 2026 cards condition falls for about forty years and then stops: houses older than that are held at 80–85% no matter their age, 11 points above the manual at the Norway median age of 52 and 30 points above it at 100 years. The sample houses from the Town’s old cards are plotted on the same axes.
Read the article · Download · Norway_Condition_vs_Age_PT103.pdf
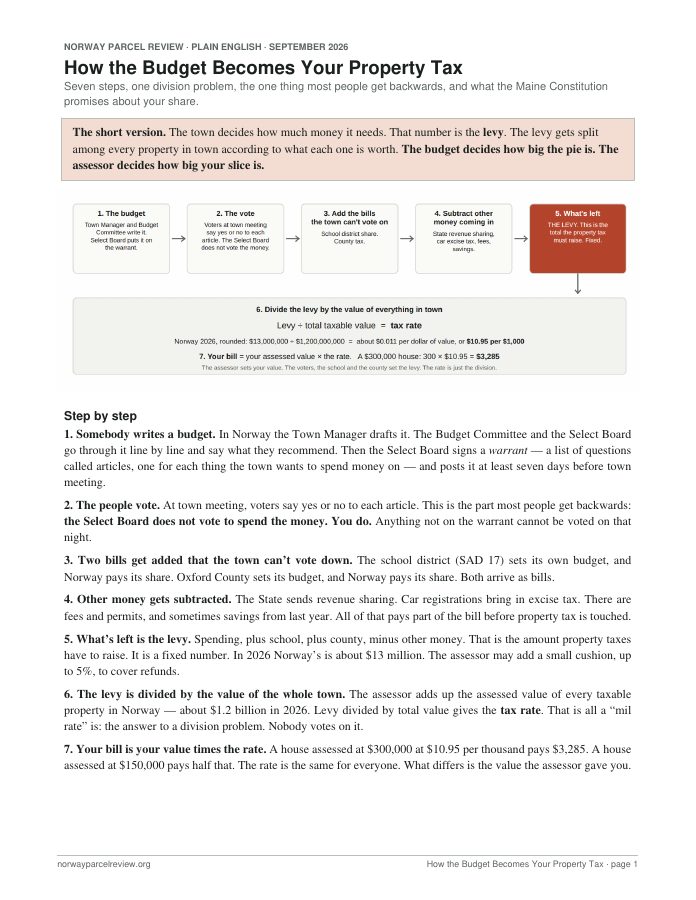
How the Budget Becomes Your Property Tax
Seven steps from the Town Manager’s draft budget to the number on your bill: the warrant, the town-meeting vote, the school and county assessments the town cannot vote down, the revenue subtracted before property tax is touched, and the levy that is left. The levy divided by the value of the whole town is the mil rate — about $13 million over about $1.2 billion in 2026. Why a revaluation cannot change how much the town raises, only who pays what share; why Norway’s rate fell from about $20 to about $11; a table of who decides each piece; and the State’s published 185-day abatement window.
Read the article · Download · Norway_How_The_Budget_Becomes_Your_Tax.pdf
Every parcel O’Donnell valued: the site-improvement charge
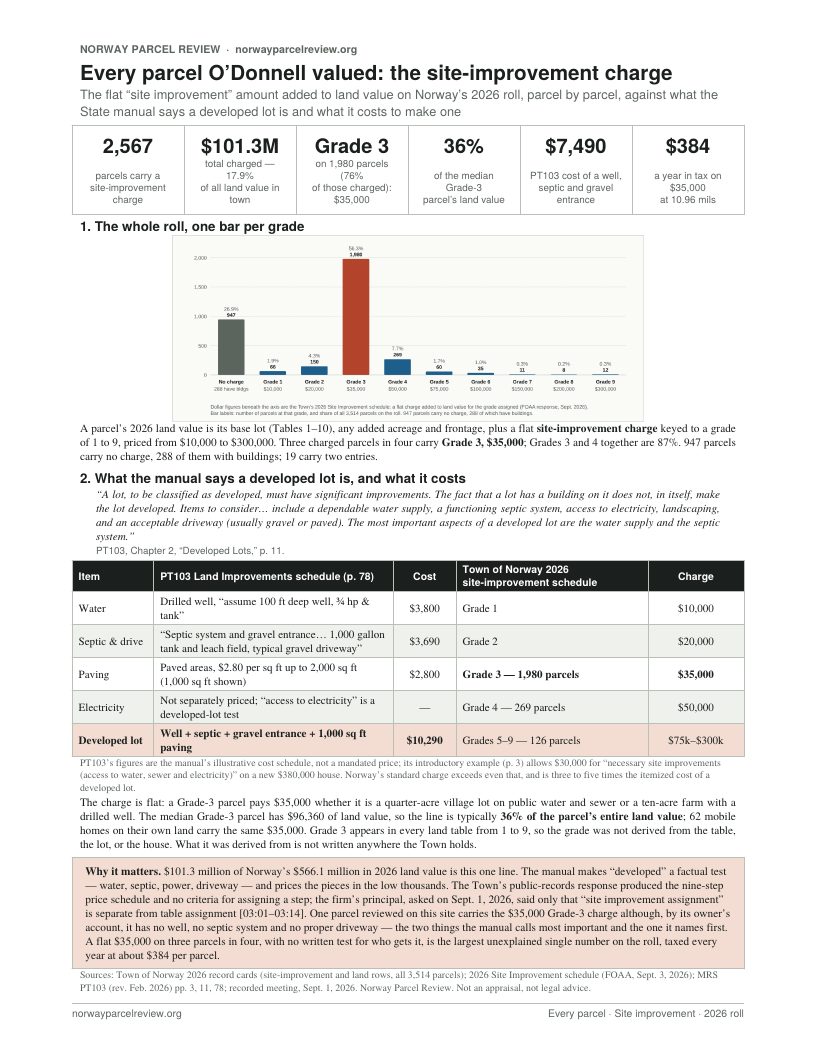
The flat site-improvement amount added to land value on all 3,514 parcels, by grade, against what the State’s assessor manual says a developed lot is — water, septic, power, driveway — and what its Land Improvements cost schedule prices those pieces at. 2,567 parcels carry a charge totalling $101.3 million, 17.9% of all land value in town. Three in four carry Grade 3, $35,000, typically 36% of the parcel’s entire land value, against roughly $10,000 in the manual for a fully developed lot. Grade 3 appears in every land table from 1 to 9, and the public-records response produced the price schedule and no criteria for assigning a grade.
Read the article · Download · Norway_Site_Improvement_vs_PT103.pdf
Every structure O’Donnell valued: building grade on the 2026 roll
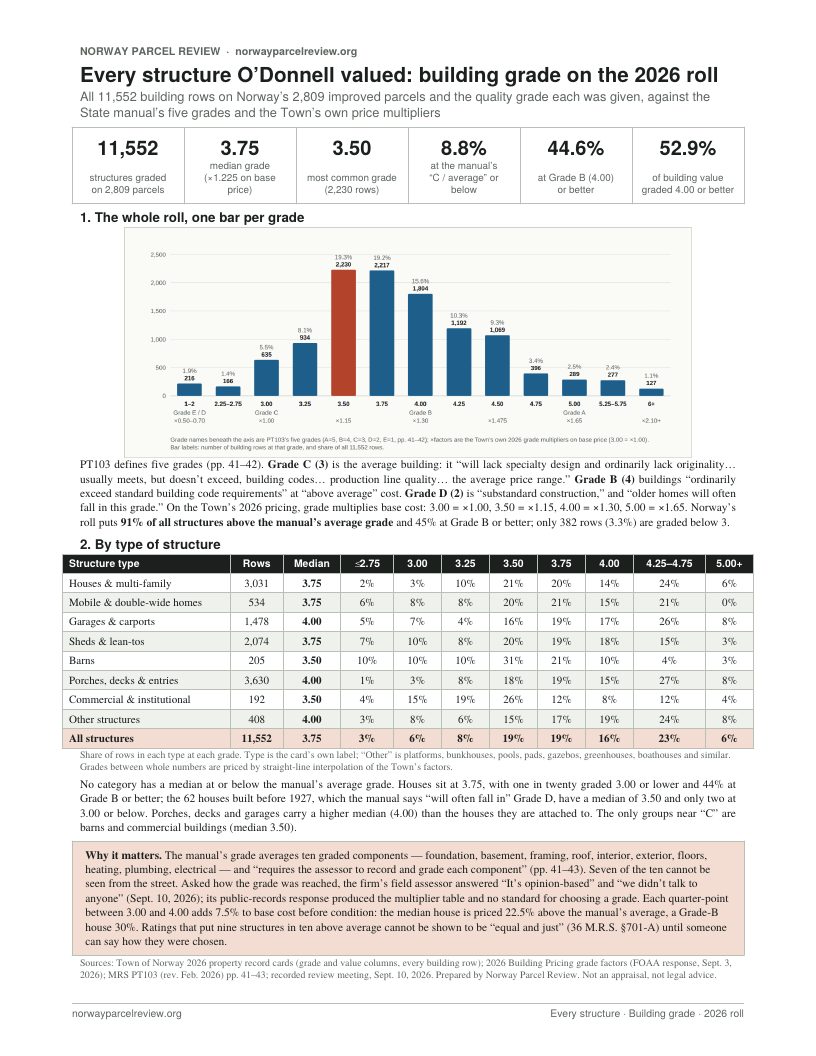
All 11,552 structures in town by the firm’s grade, with the Town’s own grade multipliers on base price. The median grade is 3.75 (×1.225 on cost), the most common 3.50. The firm has published no written definition of its 2.00–10.00 grade scale and no crosswalk to PT103’s five grade levels, so what any firm grade equals on the State’s scale is UNKNOWN. PT103’s grade averages ten components, seven of which cannot be seen from the street. Note: this PDF draws a reference to PT103’s scale; that is the State’s scale, not a measured equivalent of the firm’s numbers.
Read the article · Download · Norway_Every_Structure_Grade_2026.pdf
Every structure O’Donnell valued: condition on the 2026 roll
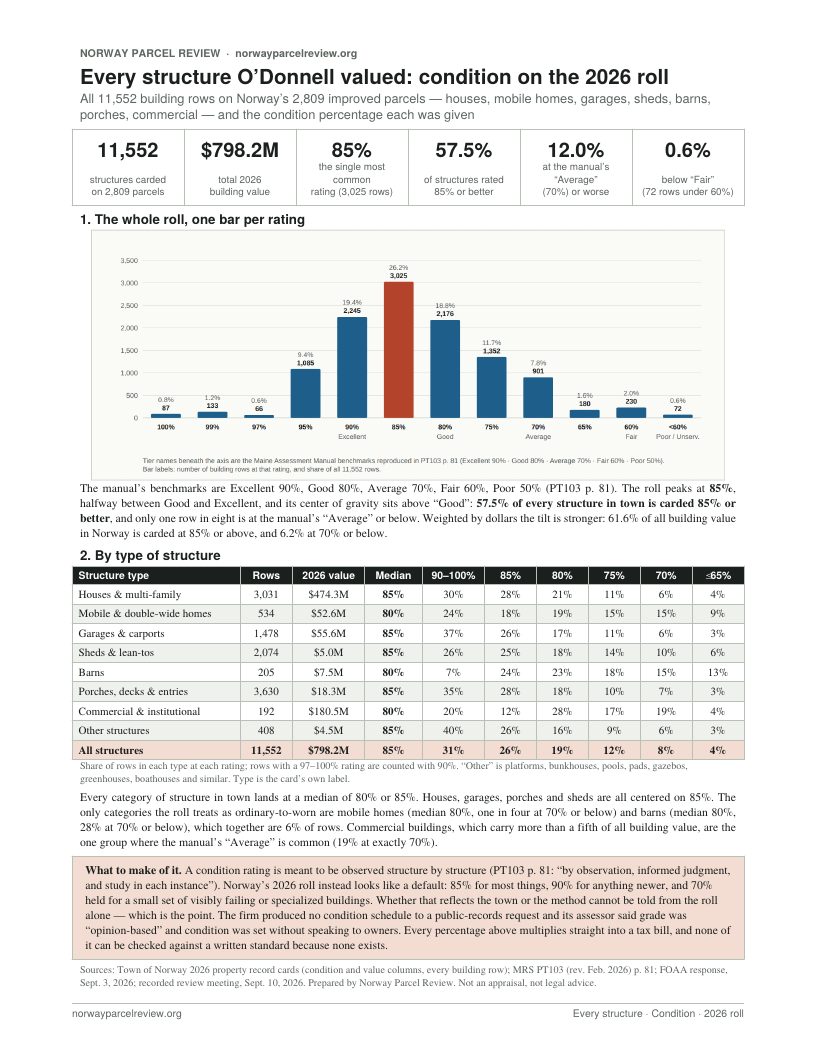
All 11,552 building rows on Norway’s 2,809 improved parcels and the condition percentage each was given, as one bar per rating and by type of structure, against the Maine Assessment Manual benchmarks in PT103 (Excellent 90% · Good 80% · Average 70%). The roll peaks at 85%; 57.5% of all structures are carded 85% or better and one in eight at the manual’s “Average” or below. Every type of structure lands at a median of 80% or 85%; only mobile homes and barns are treated as ordinary-to-worn.
Read the article · Download · Norway_Every_Structure_Condition_2026.pdf
What a shed costs, and what a shed is carded at
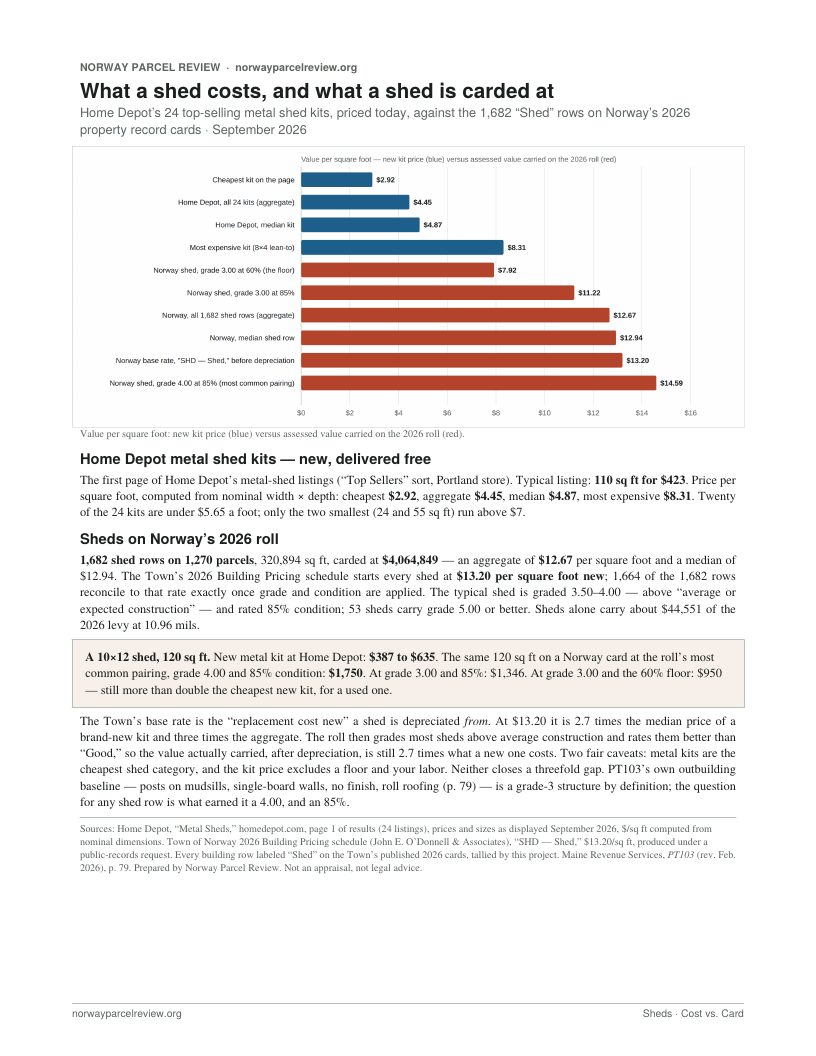
The value per square foot carried by every “Shed” row on the 2026 roll, against the price per square foot of the metal shed kits sold today at Home Depot. A question of accuracy rather than equality: the Town’s $13.20 per square foot base rate for a shed, before grade and condition are applied, set beside what a new one actually costs delivered.
Read the article · Download · Norway_Sheds_vs_Home_Depot.pdf
The End of Maine’s Municipal Property Tax Levy Cap
For nineteen years, Maine law put a second, independent ceiling on how much a town’s total property-tax levy could grow from one year to the next — a formula tied to income growth, with a separate override vote required to exceed it. In April 2024 the Legislature repealed it, by a single vote in the Senate, effective August 9, 2024. This piece explains what the 2005 law did, what L.D. 2102 changed, why the timing matters in a revaluation year, and the mil-rate mechanic that turns a valuation error into a levy an owner carries indefinitely, whatever the budget does — every thousand dollars of misapplied value is a mil’s worth of tax, every year, until the card is corrected.
Read the article · Download · Municipal_Tax_Cap_Removal_2024.pdf
More articles will be added here as they are written. Documents that are references rather than articles — charts, definitions, the levy-cap explainer’s companion piece — are on the Supplemental documents tab.
Who pays what share of the levy, before and after
The town needs to raise the same amount of money either way. The revaluation just changes who pays how much of it. The table below shows what each type of property paid in 2025, what it would pay in 2026 at the new rate of 10.96 mils, and what share of the town’s total tax bill that type of property carries. If a class’s share went up, that class is now paying for more of the town’s budget than it used to. The “added mils” column, at the far right, shows how much extra tax rate that group is really paying on top of the normal rate.
What “added mils” really means. A mil is $1 of tax for every $1,000 a property is worth. The Town says the 2026 tax rate is 10.96 mils for everyone. But that is only true if every property was valued fairly. If a property’s value was pushed up more than it should have been, that property is really paying a higher rate than 10.96 — even though the bill just says 10.96. The “added mils” column shows how much higher. Commercial and institutional buildings pay the most extra: 4.42 mils on top of the normal rate, which adds up to a 67.7% jump in their tax bill. Mobile homes pay the second most extra: 2.74 mils on top, a 33.3% jump. These are the same two classes flagged elsewhere on this site as least supported by actual sales. Single-family and multi-family houses are the only groups paying close to the normal rate, or a little less. This is not just true for whole classes of property — it is true house by house, too. A home that was overvalued is paying a higher real tax rate than a home that was undervalued, even though both are on the exact same tax roll.
Shares are of the taxable accounts on both rolls (exempt parcels, and accounts new to the 2026 roll, are excluded from the totals). Added mils = (class tax at 10.96 on the 2026 roll − class tax as billed in 2025) ÷ class 2026 taxable value × 1,000.
The class sheets
One page per class: condition bands, functional and economic obsolescence counts, land and structure change, and the effective added mils. Prepared from the 2026 cards. Norway’s card system does not carry a separate industrial class — industrial buildings are carded under the same “commercial & institutional” type as offices, retail and institutional property, so that sheet covers all three. Each chart below links to the full source document.
Single-family homes

Multi-family

Mobile and manufactured homes

Commercial & industrial

Condition, functional obsolescence and economic obsolescence — what they mean
Every building value on the 2026 roll is one multiplication: base cost (the firm’s table for the building type and size) × grade (quality of construction, 2.00–10.00) × condition (0–100%) × functional obsolescence (0–100%) × economic obsolescence (0–100%). The base cost and grade set what the building would cost to build; the other three are depreciation — everything that makes it worth less than that. The professional standard (IAAO, Standard on Mass Appraisal of Real Property) requires depreciation to be extracted from sales and documented so that any owner can reproduce it. In Norway none of the three schedules has been produced, and every factor was assigned from the outside of the building.
The order of operations in PT103
PT103 pp. 64–65 and 85–86. Information only.
- Replacement cost new from the cost schedule, using the grade.
- Less physical deterioration.
- Less functional obsolescence, calculated on replacement cost new less depreciation.
- Less external (economic) obsolescence, calculated after the first two.
Manual example: $150,000 new; 22.5% physical depreciation leaves $116,250; 10% functional leaves $104,625; 5% external leaves $99,394 (rounded to $99,400). “The overall condition of the structure is $99,400/$150,000 = 66.3%.” In PT103, then, “condition” is the combined result of all three. A Norway card shows condition, functional and economic as three separate percentages that multiply together.
Counts elsewhere on this site (11,552 building rows) are from the September 24 capture of the cards; the committed roll of October 1 has 11,515 rows, and the pages below show both.
Open each page below for the PT103 text, the IAAO text, other published views where they differ, and what Norway’s cards record.
- Building grade classifications — the state training manual’s own construction standard for what each of the ten components of a building (foundation, basement, framing, roof, interior, exterior, floors, heating, plumbing, electrical) scores 1 through 5.
- Condition — physical wear and its ladder of ratings.
- Functional obsolescence — a flaw built into the property itself.
- Economic obsolescence — a problem outside the property line.
Land tables, frontage & site improvements
Every land value on a Norway card is built from three published schedules, all prepared by John E. O’Donnell & Associates for the 2026 revaluation and produced by the Town under a public-records request: a base-acre table (a numbered Table 1–10 assigned to the parcel’s neighborhood, pricing the first acre), an additional-acreage curve for every acre after the first, and a site-improvement grade (a flat charge for the well, septic, driveway and service that make a lot usable). Waterfront parcels add a per-foot frontage price by water body. The Town’s written response to the same request was that “no written definitions exist” for what puts a parcel in one table rather than another.
The ten land tables — first acre and the acres after it
| Table | First acre | Each additional acre, by band | Parcels on this table |
|---|---|---|---|
| Table 1 | $30,600 | 0–3 ac: $3,100 · 3–25 ac: $1,500 · 25+ ac: $750 | 1 |
| Table 2 | $42,000 | 0–3 ac: $4,200 · 3–25 ac: $2,000 · 25–50 ac: $1,000 · 50+ ac: $750 | 11 |
| Table 3 | $52,000 | 0–3 ac: $5,200 · 3–25 ac: $3,000 · 25–50 ac: $1,000 · 50+ ac: $750 | 1,733 |
| Table 4 | $62,000 | 0–10 ac: $6,200 · 10–25 ac: $3,000 · 25–50 ac: $1,000 · 50+ ac: $750 | 790 |
| Table 5 | $78,000 | 0–10 ac: $7,800 · 10–25 ac: $3,000 · 25–50 ac: $1,000 · 50+ ac: $750 | 74 |
| Table 6 | $94,000 | 0–10 ac: $9,400 · 10–25 ac: $3,000 · 25–50 ac: $1,000 · 50+ ac: $750 | 77 |
| Table 7 | $112,000 | 0–10 ac: $11,200 · 10–25 ac: $3,000 · 25–50 ac: $1,000 · 50+ ac: $750 | 96 |
| Table 8 | $160,000 | 0–10 ac: $16,000 · 10–25 ac: $3,000 · 25–50 ac: $1,000 · 50+ ac: $750 | 71 |
| Table 9 | $225,000 | 0–10 ac: $22,500 · 10–25 ac: $3,000 · 25–50 ac: $1,000 · 50+ ac: $750 | 341 |
| Table 10 | $300,000 | 0–10 ac: $30,000 · 10–25 ac: $3,000 · 25–50 ac: $1,000 · 50+ ac: $750 | 1 |
First-acre value is the base-acre schedule’s figure at 1.00 acre; smaller lots are priced on a curve below it (a quarter-acre on Table 3, for example, is $36,920). “Parcels on this table” counts every 2026 card whose land rows use that table. Two-thirds of the town sits on Table 3 — the one O’Donnell described at the September 1 hearing as “the generic table that’s probably the vast majority of town” — and Tables 1, 2 and 10 are barely used at all.
Read the additional-acre column carefully: on Tables 4 through 10, every acre up to the tenth is priced at the full first-tier rate, and the price does not drop until the eleventh acre. A fourteen-acre lot on Table 4 is therefore carded at ten acres × $6,200 plus four × $3,000. The schedule makes no distinction between an acre that can be built on and one that cannot; a separate “Wasteland” land row exists for that — it appears on 27 cards on the 2026 roll, at nominal figures such as $250 for five acres — but whether a parcel gets one is, again, undefined in writing.
Waterfront frontage — price per foot, by water body
| Water body | First 50 ft | 50–100 | 100–200 | 200–300 | 300–500 | 500–1,000 |
|---|---|---|---|---|---|---|
| Pennesseewassee Lake | $3,500 | $2,450 | $1,050 | $700 | $500 | $375 |
| Sand Pond | $2,500 | $1,750 | $875 | $625 | $500 | $375 |
| North Pond | $2,500 | $1,750 | $875 | $625 | $500 | $375 |
| North Pond North | $1,750 | $1,225 | $612 | $175 | $175 | $175 |
| Little Pennesseewassee Pond | $1,250 | $875 | $437 | $312 | $250 | $187 |
Per front foot. The first fifty feet carry the full rate; each band beyond is a declining share of it. A 200-foot North Pond lot is carded at 50 × $2,500 + 50 × $1,750 + 100 × $875 = $300,000 of frontage before the land table is applied. See Waterfront burden for what that did to lake bills.
Site improvements — a flat charge by grade
| Grade | Charge | Parcels at this grade |
|---|---|---|
| Grade 1 | $10,000 | 66 |
| Grade 2 | $20,000 | 150 |
| Grade 3 | $35,000 | 1,980 |
| Grade 4 | $50,000 | 269 |
| Grade 5 | $75,000 | 60 |
| Grade 6 | $100,000 | 35 |
| Grade 7 | $150,000 | 11 |
| Grade 8 | $200,000 | 8 |
| Grade 9 | $300,000 | 12 |
The site-improvement grade is meant to price what has been done to make a lot usable — well, septic, driveway, utility service. Grade 3, $35,000, is on 1,980 parcels. No schedule was produced describing what earns Grade 2 rather than Grade 3, and this site has reviewed at least one lot carrying $20,000 of site improvements with no well, no septic, and no proper driveway.
Building grade
Buildings are graded on a separate 1–10 scale in O’Donnell’s schedule (the Town’s 2026 Building Pricing table lists a factor for each step: grade 3 = 1.00, grade 4 = 1.30, grade 5 = 1.65). The State’s own manual, PT103, grades on a 1–5 scale with a written description of every criterion. The firm has published no written definition of its 2.00–10.00 grade scale and no crosswalk to PT103’s five grade levels, so what any firm grade equals on the State’s scale is UNKNOWN. The next two pages in this section reproduce the State’s grade classifications and put them in a calculator that applies the State’s classifications to a card’s figures.
Building grade classifications (PT103) → · Building grade calculator →
Sources: Town of Norway 2026 Base Acre Pricing, Additional Acreage Pricing, Waterfront FF Pricing, Site Improvement Pricing and Building Pricing schedules (John E. O’Donnell & Associates), produced under a Freedom of Access Act request, Sept. 2026; the Town’s written response to item 3 of that request (“No written definitions exist”); parcel counts tallied from the Town’s published 2026 cards. Charts of the land tables and site-improvement schedule are on the Supplemental documents tab.
Every parcel O’Donnell valued: the site-improvement charge (PDF, 1 page) — the site-improvement grade on all 3,514 parcels, against PT103’s developed-lot test and its Land Improvements cost schedule.
Building grade classifications, grades 1–5 (all ten PT103 components)
Grade measures quality of construction. Maine’s own assessor-training curriculum breaks a building into ten components — foundation, basement, framing, roof, interior, exterior, floors, heating, plumbing and electrical — each scored on the same five-point scale and averaged to produce the building’s overall grade. The five grades are lettered A through E and carry the point values A (5), B (4), C (3), D (2) and E (1), running from architecturally designed, contractor-built construction at the top to basic, inadequate shelter at the bottom.
The tables below are the manual’s own component-by-component grading schedule: the physical construction standard an assessor is trained to look for when scoring each of the ten components at each grade level, starting with foundation.
1. Foundation
| Grade 1 (E) | Grade 2 (D) | Grade 3 (C) | Grade 4 (B) | Grade 5 (A) |
|---|---|---|---|---|
|
|
|
|
|
*Printed exactly as “Wall, poured concrete 8” 7’” in the source with no separating punctuation; read in context as an 8-inch-thick wall at 7 feet in height, alongside the 7-foot concrete block wall as an alternative Grade 3 wall construction.
Read down each column: the manual lists the construction features an assessor is trained to find present at that grade level, from bare excavation and wood posts at Grade 1 to a full-height poured-concrete wall, insulation, two-sided drain tile and ample finish grading at Grade 5. These are the features associated with each grade, not a strict checklist — the manual does not state a minimum number of items a foundation must have to earn a given grade.
Alternate foundation types
The same schedule separately assigns grade-point values to specific foundation types that fall outside the excavation/footing/wall structure above — posts, sonotubes and frost walls typically used under slab or crawlspace construction:
| Foundation type | Grade points | Note in manual |
|---|---|---|
| Wood posts on concrete pads | 1.5 | — |
| Concrete posts (sonotubes) | 2 | — |
| Frost wall, 8" poured concrete | 3 | Deduction for no basement |
| Frost wall, concrete block | 3 | Deduction for no basement |
| Pressure-treated wood walls | 2 | — |
This is state training material for assessors, not Norway’s own cost schedule. The O’Donnell cards used for the 2026 revaluation express grade as a single multiplier (see the Condition & obsolescence guide), and neither the firm’s own grade schedule nor its component-specific criteria have been published for Norway. These tables are the state’s own published standard for what a given component grade is supposed to represent physically — a benchmark for comparing what a card claims against what a building actually is.
Source: Maine Revenue Services, Property Tax Division, PT103 — Valuation of Real Estate (rev. February 2026), Chapter 3 “Measuring and Listing,” “Grading Schedules,” foundation through electrical, pp. 50–57 (five-grade descriptions, pp. 41–42). Read the full manual (PDF, maine.gov).
Every structure O’Donnell valued: building grade on the 2026 roll (PDF, 1 page) — how the grades above were actually applied across all 11,552 structures in town.
Calculate Building Grade per the State of Maine Guidebook
Maine Revenue Services’ assessor-training manual, PT103 — Valuation of Real Estate, publishes a grading schedule for all ten components of a building — foundation, basement, framing, roof, interior, exterior, floors, heating, plumbing, electrical — with the State’s own description of what Grade 1 through Grade 5 looks like for each criterion, and a worked method for averaging them into a total building grade (Chapter 3, pp. 41–42, 50–57).
The calculator applies that schedule, and nothing else, to a building you describe. Open it from the Calculate Building Grade link on any parcel card and that card’s figures come with you; or open it directly and grade any building from scratch. It walks you through the ten components, shows every step of the arithmetic, and gives you a plain-text summary of the arithmetic.
The result is an estimate on the State’s 1–5 scale. The grade on your card comes from O’Donnell & Associates’ own schedule, which runs 1–10 and has no published written definitions; the two are not interchangeable numbers, and how a firm grade corresponds to a State grade is UNKNOWN. What the calculator gives you is the State’s description of your building, criterion by criterion, in the State’s own words.
Condition (“percent good”): the standard and the 2026 cards
“PT103” is Valuation of Real Estate, Maine Revenue Services assessor-training course (Chapter 4, The Cost Approach). “IAAO” is the International Association of Assessing Officers. Page numbers are the manual’s printed page numbers. Norway figures are counts of building rows on the 2026 property record cards, shown for the September 24 capture and for the committed roll. This page describes; it does not say what any owner should do, and it is not legal advice or an appraisal.
What PT103 says
- Definition (p. 80). “Condition is equal to the value of property after depreciation, divided by the property value before depreciation.” Depreciation is the difference between replacement cost new and market value.
- What it includes (pp. 64–65). Condition is the value of a structure “after wear and tear and obsolescence have been recognized.” Physical deterioration plus functional and external obsolescence together are depreciation. A building with 25% depreciation is in 75% condition. Condition applies whatever the grade: “Grade is associated with construction, while condition is associated with destruction.”
- How it is set (p. 81). By the direct (“breakdown”) method, inspecting the structure’s components, correlated with the marketplace. “Depreciation must be determined by observation, informed judgment, and study in each instance.” The actual physical condition and the structure’s relationship to comparable structures must be taken into account.
- Benchmarks (p. 81). Excellent 90% condition (10% depreciation); Good 80%; Average 70%; Fair 60%; Poor 50%; Unserviceable below 50%, “according to degree of deterioration.”
- Age example (pp. 64–65). A 45-year-old ranch house: recent sales showed about one-half percent depreciation per year, 45 × 0.5% = 22.5%, so 77.5% condition.
- Date (pp. 81–82). Condition is as of April 1. Only past events count; a demolition scheduled for April 2 does not affect April 1.
What the IAAO says
- Glossary. Depreciation is the loss in value relative to replacement cost new from any cause; it is sometimes divided into physical deterioration, functional obsolescence and external obsolescence (quoted in PT103 p. 80).
- Standard on Mass Appraisal of Real Property. Depreciation estimates should rest on non-cost (sales) data and schedules should be extracted from sales; subjective codes such as grade and condition should be coded correctly at least 90% of the time and objective characteristics 95%; on-site review of property characteristics at least every 4 to 6 years.
Other published scale (not a Maine standard)
The lending industry’s Uniform Appraisal Dataset rates condition C1 to C6. The assessment-manual “CDU” ladders descend from Marshall & Swift. They are listed here because several of them describe each step in words; PT103 gives the percentages above.
| Percent good | CDU term | UAD | What the published ladders describe |
|---|---|---|---|
| 97–100% | Excellent | C1–C2 | New or as new; no visible deterioration |
| 90–95% | Very good | C2–C3 | Slight deterioration, curable with normal maintenance |
| 80–85% | Good | C3–C4 | Minor deterioration; well maintained |
| 70–75% | Average | C4 | Normal wear for age; modest deferred maintenance |
| 60–65% | Fair | C4–C5 | Marked deferred maintenance, but occupied and usable |
| 40–55% | Poor | C5 | Definite deterioration; livability diminished; major repairs required |
| 20–35% | Very poor | C6 | Structural faults not economically curable |
| 0–20% | Unsound | C6 | Unfit for use; end of useful life |
Note that the two scales do not match step for step: PT103 puts Poor at 50% and Unserviceable below it; the CDU ladder puts Poor at 40–55%.
What Norway’s 2026 cards record
Building rows by condition rating, set against PT103’s benchmarks.
| Rating | PT103 p. 81 benchmark | Sept. 24 cards | Committed roll (Oct. 1) |
|---|---|---|---|
| 95–100% | Above the manual’s “Excellent” benchmark | 1,367 | 1,351 |
| 90% | Excellent (benchmark) | 2,245 | 2,163 |
| 85% | Between Good and Excellent | 3,025 | 2,978 |
| 80% | Good (benchmark) | 2,176 | 2,211 |
| 75% | Between Average and Good | 1,352 | 1,415 |
| 70% | Average (benchmark) | 901 | 900 |
| 65% | Between Fair and Average | 180 | 180 |
| 60% | Fair (benchmark) | 230 | 235 |
| 55% | Between Poor and Fair | 1 | 1 |
| 50% | Poor (benchmark) | 47 | 55 |
| Below 50% | Unserviceable | 24 | 26 |
| All building rows | 11,548 | 11,515 |
The Town has not produced a depreciation schedule, and the cards were prepared from the street, not inside the buildings.
Selected cards, side by side
The September 24 capture is the first set of cards obtained; the committed roll is the version committed October 1.
| Parcel | Sept. 24 card (main building) | Committed roll (main building) |
|---|---|---|
| 12 King Street | Light Industrial: cond 75%, func 90%, econ 90% | Light Industrial: cond 65%, func 65%, econ 90% |
| 14 King Street | Multi-Family: cond 60%, func 80%, econ 100% | Multi-Family: cond 50%, func 50%, econ 100% |
| 16 King Street | 1-Story Frame: cond 60%, func 80%, econ 100% | 1-Story Frame: cond 50%, func 50%, econ 100% |
| 15 King Street | Multi-Family: cond 85%, func 100%, econ 100% | Multi-Family: cond 85%, func 100%, econ 100% |
| 87 Point Lane | 1-Story Frame: cond 90%, func 100%, econ 100% | 1-Story Frame: cond 85%, func 100%, econ 100% |
| 523 Norway Center Road | 1½-Story Frame: cond 60%, func 90%, econ 100% | 1½-Story Frame: cond 60%, func 90%, econ 100% |
Condition ratings, by percentage
Every building row on a Norway card carries a condition percentage. This page explains each one that appears on the 2026 roll: where it sits on the State’s own scale, how old a building it describes, what PT103’s inspection list describes behind it, and real parcels on the roll that carry it. The Cond. figure on every parcel card on this site links here.
Jump to: 100% · 99% · 97% · 95% · 90% · 85% · 80% · 75% · 70% · 65% · 60% · Below 60%
Read with the plain-English explainer, the Condition page (the industry ladder, C1–C6), and the townwide distribution chart. Grade is a separate question from condition: “grade is associated with construction, while condition is associated with destruction” (PT103 p. 64), and “a high-quality house, Grade 5, might be in the poorest condition of any house in town” (p. 65).
100% — no depreciation at all
PT103 defines condition as “the value of property after depreciation, divided by the property value before depreciation” (p. 80). A 100% card therefore asserts that the building has lost nothing — no wear, no age, no design shortfall, no outside influence. The manual’s own scale tops out at “Excellent,” 90%; 100% is a brand-new building, or one the assessor has not yet depreciated at all.
On the Norway roll, 100% is uncommon and mostly literal: the houses carrying it are 2025–2026 builds still under construction, or older houses gutted and mid-renovation, each carded with a reduced functional factor (20–40%) to reflect the unfinished state. A finished, lived-in house showing 100% with no functional reduction is a card asserting it has not aged a day. As this site says elsewhere, 100% is the assessor’s starting position, not a finding that nothing is wrong.
- 41 Orchard St — Frame house, 1 storey, 1-Story Frame, 1252 sq ft, grade 3.75, built 1941; row value $94,118 (F.Obs 40%).
- 135 Needham Rd — Frame house, 1 storey, 1-Story Frame, 512 sq ft, grade 4.00, built 2026; row value $34,909 (F.Obs 25%).
- 49 Penn Rd — Frame house, 1 storey, 1-Story Frame, 1458 sq ft, grade 4.25, built 2026; row value $53,574 (F.Obs 20%).
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
99% — above “Excellent”
At the manual’s illustrative rate of “approximately one-half percent per year” (p. 64), 99% is a building about two years old with nothing wrong with it. The roll agrees: the median house rated 99% was built in 2024.
What PT103’s inspection list describes for a 99% house (pp. 36–37): a dry basement, no settling or framing issues, plumbing and electrical of current type and age, a modern heating plant, a straight roofline, and roofing and siding with no visible wear.
- 25 Yagger Rd.. — Frame house, 1½ storey, 1½-Story Frame, 1064 sq ft, grade 4.50, built 2023; row value $314,299.
- 547 Crockett Ridge Rd — Frame house, 1 storey, 1-Story Frame, 1510 sq ft, grade 4.50, built 2024; row value $290,674.
- 45 Mayflower Way — Frame house, 1½ storey, 1½-Story Frame, 1724 sq ft, grade 6.00, built 2025; row value $579,177.
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
97% — above “Excellent”
A rarely used step on Norway’s roll (66 rows). At the manual’s half-percent-per-year rate it describes a building roughly six years old with no defects; the median house rated 97% here was built in 2024. Everything said of 99% applies.
- 1201 Crockett Ridge Rd — Frame house, 1½ storey, 1½-Story Frame, 858 sq ft, grade 4.50, built 2015; row value $261,941.
- 60 Overlook Dr — Frame house, 1 storey, 1-Story Frame, 1232 sq ft, grade 4.50, built 2024; row value $276,487.
- 43 Overlook Dr — Frame house, 1 storey, 1-Story Frame, 1456 sq ft, grade 4.50, built 2025; row value $302,605.
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
95% — above “Excellent”
A 95% card asserts five percent total depreciation — at the manual’s rate, a ten-year-old building with nothing wrong with it. The median house rated 95% on the roll was built in 2019, which fits. Anything visibly worn or past due — a roof at end of life, failed window seals, a boiler beyond its service life — is incompatible with this tier by the manual’s own worked example, which puts a house with dented siding and an overdue roof at 77.5% (pp. 64–65).
- 193 Parsons Rd — Frame house, 1¾ storey, 1¾-Story Frame, 1356 sq ft, grade 5.25, built 2004; row value $444,843.
- 62 Shore Ln — Frame house, 2 storey or more, 2-Story Frame, 660 sq ft, grade 4.25, built 2019; row value $219,044.
- 101 Sandy Shore Ln — Frame house, 1 storey, 1-Story Frame, 1772 sq ft, grade 5.75, built 2023; row value $402,324.
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
90% — “Excellent”
90% is the Maine Assessment Manual’s “Excellent” benchmark (PT103 p. 81). There is nothing above it but a new building. At the manual’s half-percent-per-year rate it is a house about twenty years old with ordinary age and nothing else; the roll’s median 90% house was built in 2002, twenty-four years ago, which is close.
What the manual says an inspector should find behind a 90%: the basement list on pp. 36–37 comes back clean — “water and other condition problems,” “settling and framing issues,” “electrical rating and age,” “plumbing/piping quality” all unremarkable. Any deferred maintenance at all moves a building off this tier: the manual’s example house with cosmetic siding damage and shingles “five years past due” is 77.5%, two full tiers down.
Where a 90% rating sits high for its group: a 1970 one-story cottage on Point Lane rated 90% (in the top 12% of Norway’s pre-1975 one-story houses); the two open-porch rows on a 2006 Crockett Ridge Road farmhouse rated 90% although the rear porch must be rebuilt from its supports up; and a rough-sawn, unsided, non-weather-tight pole barn on Larson Road rated 90% at grade 4.25. The farmhouse itself at 90% is, by contrast, exactly what the manual’s rate predicts for a 2006 build.
- 191 Roberts Rd — Frame house, 1 storey, 1-Story Frame, 1040 sq ft, grade 3.75, built 1974; row value $188,135.
- 142 Parsons Rd — Frame house, 1 storey, 1-Story Frame, 1822 sq ft, grade 4.50, built 2003; row value $324,995.
- 164 Upton Brothers Rd — Frame house, 1 storey, 1-Story Frame, 1728 sq ft, grade 4.50, built 2010; row value $324,103.
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
See the one-page explainer What does “90% condition” actually mean? and the Crockett Ridge Road and Larson Road assessment reviews on this site.
85% — between “Good” (80%) and “Excellent” (90%)
85% is the single most common rating on the 2026 roll: 3,025 of 11,552 building rows, more than one in four, and the median row townwide. It is the roll’s definition of “normal.” It is not the manual’s. On the PT103 scale “Average” is 70%; 85% asserts only fifteen percent total depreciation — at the manual’s rate, a thirty-year-old house with nothing wrong with it.
Here is the mismatch in one number: the median house rated 85% on Norway’s roll was built in 1979 — forty-seven years old. The manual’s own worked example is a forty-five-year-old ranch with dented, faded siding and an overdue roof, and it comes out at 77.5% (pp. 64–65). The roll routinely places houses of that age seven and a half points above the manual’s example of a tired one.
What PT103’s scale describes at 85%: normal wear for age, every major component functional, nothing past due. The manual describes a house with a failing foundation, an original boiler, uninsulated framing, inoperable windows, a leaning chimney, or sagging plaster at a lower tier.
- 2 Nevers Ave — Frame house, 1¾ storey, 1¾-Story Frame, 672 sq ft, grade 3.75, built 1947; row value $170,605.
- 51 Valhalla Ln — Frame house, 1 storey, 1-Story Frame, 584 sq ft, grade 3.50, built 1979; row value $105,769.
- 111 Point Ln — Mobile / manufactured home, Mo Ho 12-Foot, 648 sq ft, grade 3.50, built 2001; row value $50,864.
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
See the one-page explainer What does “85% condition” actually mean? and the King Street assessment review on this site (a multifamily carded 85% with a failing foundation, ~30-year boiler, and eleven inoperable windows, on a visit the card records as “Refused”).
80% — “Good”
80% is the Maine Assessment Manual’s “Good” benchmark (PT103 p. 81): a building with a fifth of its value gone to wear and obsolescence — at the manual’s rate, roughly forty years old and otherwise sound. The roll’s median 80% house was built in 1971, fifty-five years ago.
In practice this is a house with normal wear for its age where some components are at or near the end of their life but still working: an older roof that does not yet leak, a furnace on its last years, original windows that still close. The manual’s example house — dented siding, roof five years overdue — sits just below this line at 77.5%, so a house with visible exterior deferred maintenance belongs below 80%, not at it.
- 23 Hayden Ave — Frame house, 1 storey, 1-Story Frame, 884 sq ft, grade 3.50, built 1927; row value $140,080.
- 16 Marion Ave — Frame house, 1 storey, 1-Story Frame, 1113 sq ft, grade 3.50, built 1971; row value $165,110.
- 24 Meadow Brook Dr — Frame house, 1 storey, 1-Story Frame, 960 sq ft, grade 3.75, built 1992; row value $158,170.
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
75% — between “Average” (70%) and “Good” (80%)
This is where the manual’s own example house lands on physical wear alone: a forty-five-year-old ranch whose aluminum siding is “pockmarked with dents” and faded and whose “roofing shingles are five years past due for replacement” — 77.5% (pp. 64–65). So 75% describes a house with visible, cosmetic-to-moderate exterior wear and at least one component past due, before any functional deduction. The roll’s median 75% house was built in 1963.
- 40 Greenleaf Ave — Frame house, 1¾ storey, 1¾-Story Frame, 728 sq ft, grade 3.50, built 1920; row value $147,923.
- 217 Waterford Rd — Frame house, 1 storey, 1-Story Frame, 1216 sq ft, grade 3.50, built 1964; row value $160,142.
- 733 Greenwood Rd — Mobile / manufactured home, Mo Ho 14-Foot, 924 sq ft, grade 3.00, built 1991; row value $58,281.
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
70% — “Average”
70% is what the Maine Assessment Manual calls Average (PT103 p. 81). It is where the manual’s worked example nets out once the substandard basement is counted — 77.5% physical, less a 10% functional deduction — and it is the manual’s picture of an ordinary, somewhat tired house: cosmetic siding damage, an overdue roof, a low basement. Only 901 rows on Norway’s roll (7.8%) were rated here. The State’s “average” is, on this roll, a below-average rating.
Because 70% is also the bottom of the range the firm applies to most occupied houses, it is doing double duty: on the roll it is the rating for an 1880 farmhouse on Round the Pond Road, for a 1930 one-story house on Waterford Road, and for a century-old cattle barn on Crockett Ridge Road that is missing an entire wall. On the manual’s own half-percent rate, a hundred-year-old structure is near 50% from age alone, before any specific damage.
- 78 Harrison Rd — Frame house, 1 storey, 1-Story Frame, 712 sq ft, grade 3.25, built 1936; row value $92,405.
- 7 Roberts Rd — Mobile / manufactured home, Mo Ho 12-Foot, 768 sq ft, grade 2.00, built 1972; row value $30,218.
- 436 Round The Pond Rd — Mobile / manufactured home, Mo Ho 14-Foot, 924 sq ft, grade 3.50, built 1988; row value $62,555.
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
See the Crockett Ridge Road assessment review (barn, cattle barn, garage and milk-stall shed all at 70%, and a single-wide mobile home at 70%) and the Larson Road review (the neighboring barn used as a comparable at 70%).
65% — between “Fair” (60%) and “Average” (70%)
A lightly used step (180 rows), applied mostly to older mobile homes and small pre-war houses. It describes a building with visible deferred maintenance where several components need repair or replacement, but which is still fully in service. If the roll has put a structure here, the assessor has already conceded it is below the State’s average; the question for the owner is whether it belongs lower still.
- 299 Harrison Rd — Frame house, 2 storey or more, 2-Story Frame, 624 sq ft, grade 3.50, built 1936; row value $127,422.
- 30 Hart Dr — Mobile / manufactured home, Mo Ho 12-Foot, 672 sq ft, grade 2.50, built 1977; row value $29,814.
- 15 Hidden Acres Ln — Mobile / manufactured home, Mo Ho 12-Foot, 1064 sq ft, grade 3.50, built 1992; row value $66,109.
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
60% — “Fair”
60% is the manual’s “Fair” benchmark: substantial deferred maintenance, with major components — roof, systems, sills — due. On the September 24 cards it is also, in practice, a floor: 230 rows sit exactly on it and only 72 of 11,552 fall beneath it. That was the rating on 16 King Street (no running water or heat, listed as a tear-down at $60,000, building carded at $76,080) and 14 King Street (no kitchen, bath, water, sewer or power, parcel carded at $204,090). On the committed roll both are rated 50%.
The manual’s scale does not stop at 60%. Below “Fair” come “Poor” (50%) and “Unserviceable,” defined as more than 50% depreciation “according to degree of deterioration” (p. 81). On the industry ladder a building without water, heat or power is C5–C6, 20–40%. When a derelict structure and an occupied, worn house both carry 60%, one of the two ratings is wrong — and the occupied house next door has a ready comparable.
- 99 Waterford Rd — Frame house, 1 storey, 1-Story Frame, 704 sq ft, grade 3.25, built 1940; row value $83,740.
- 66 Lake Rd — Mobile / manufactured home, Mo Ho 12-Foot, 624 sq ft, grade 2.00, built 1972; row value $21,045.
- 625 Round The Pond Rd — Mobile / manufactured home, Mo Ho 14-Foot, 742 sq ft, grade 2.00, built 1981; row value $26,209.
Three parcels chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
See the Condition page’s examples for 14 and 16 King Street and 523 Norway Center Road.
Below 60% — “Poor” (50%) and “Unserviceable” (below 50%)
Seventy-two rows on the entire roll — 0.6% — are rated below 60%: one at 55%, 47 at 50%, and 24 scattered from 40% down to 20%. The manual’s “Poor” benchmark is 50%; below that is “Unserviceable,” rated “according to degree of deterioration” (p. 81). These are buildings with significant deterioration, parts unusable, or structural or system failure — a structure needing major work to be habitable, or a tear-down with salvage value only.
The manual’s April 1 rule matters most here: condition must reflect the structure “as of April 1,” counting “only past events” (pp. 81–82). PT103 states that the rating reflects the structure as of April 1, counting only past events.
- 276 Wiley Rd — Mobile / manufactured home, Mo Ho 14-Foot, 840 sq ft, grade 2.00, built 1978; row value $24,726.
The one main dwelling with a build year on the card chosen from the roll to span the range of build years at this rating, not hand-picked for effect. Click any to open its card.
Sources: Maine Revenue Services, PT103 — Valuation of Real Estate (rev. Feb. 2026), pp. 36–37, 64–65, 80–82; Town of Norway 2026 property record cards (all 11,552 building rows across 3,514 accounts), tallied by this site; this site’s assessment reviews for King Street, Crockett Ridge Road and Larson Road, and its one-page explainers on 85% and 90% condition. Industry terms per IAAO Glossary and Fannie Mae/UAD condition ratings C1–C6, as on the Condition page. Median build years use only rows with a year on the card.
Every structure O’Donnell valued: condition on the 2026 roll (PDF, 1 page) — the full distribution and a breakdown by type of structure, on one printable page.
Functional obsolescence: the standard and the 2026 cards
“PT103” is Valuation of Real Estate, Maine Revenue Services assessor-training course (Chapter 4, The Cost Approach). “IAAO” is the International Association of Assessing Officers. Page numbers are the manual’s printed page numbers. Norway figures are counts of building rows on the 2026 property record cards, shown for the September 24 capture and for the committed roll. This page describes; it does not say what any owner should do, and it is not legal advice or an appraisal.
What PT103 says
- Definition (p. 65). “A decrease in value due to a change in demand, usually because of a shift in consumer tastes or of market standards.” It is calculated the same way as depreciation, on replacement cost new less depreciation.
- IAAO definition quoted (p. 82). A “[l]oss in value of a property resulting from changes in tastes, preferences, technical innovations, or market standards.” It results from causes contained within the structure itself.
- The test (p. 82). Ask whether a similar structure built today would keep all the general characteristics of the subject property in design, size, materials and facilities.
- Curable or incurable (p. 82). Curable: a lack that is easily corrected, such as the need for a second bathroom. Incurable: not economically feasible to cure, such as poor room layout.
- Categories (pp. 82–83). Super-adequacy (a quality higher than current standards); inadequacy (falls short of market expectations: too small, too few rooms, limited facilities, lack of storage); lack of desirability; eccentric design; atypical layouts (poor use of floor area, access to the rest of the home through a bedroom); outmoded equipment (plumbing, electrical outlets and GFI, heating such as a fireplace as the only heat or no central heat).
- No double counting (p. 65). A grade reduction and functional obsolescence should not be applied to the same feature. Manual example: lesser-quality vinyl siding is a grade matter; a single bathroom in a house where new houses have two is functional obsolescence.
- Worked example (pp. 65, 85–86). A basement with six feet of headroom: municipal studies show 10% functional obsolescence, so $116,250 × 0.90 = $104,625. A one-bath house carries 5% in the manual’s later example.
What the IAAO says
The IAAO Glossary defines functional obsolescence as loss in value from lack of utility or desirability inherent to the improvement. The Standard on Mass Appraisal calls for depreciation schedules extracted from sales data.
What Norway’s 2026 cards record
| Factor | Measure | Sept. 24 cards | Committed roll (Oct. 1) |
|---|---|---|---|
| Functional obsolescence | Building rows below 100% | 794 of 11,548 | 1,576 of 11,515 |
| Parcels with at least one | 281 | 674 | |
| Economic obsolescence | Building rows below 100% | 102 of 11,548 | 103 of 11,515 |
| Parcels with at least one | 78 | 78 |
Most frequent building types with a functional markdown, committed roll: Open Porch (OP) (210), Mo Ho 14-Foot (207), Deck (142), Shed (123), Enclosed Porch (EP) (122), 1-Story (120), Barn (73), 1-Story Frame (72).
Most frequent, September 24 cards: Open Porch (OP) (89), Shed (89), 1-Story (85), Enclosed Porch (EP) (63), Barn (62), 1-Story Frame (51), Garage (49), Deck (44).
Selected cards, side by side
| Parcel | Sept. 24 card (main building) | Committed roll (main building) |
|---|---|---|
| 12 King Street | Light Industrial: cond 75%, func 90%, econ 90% | Light Industrial: cond 65%, func 65%, econ 90% |
| 14 King Street | Multi-Family: cond 60%, func 80%, econ 100% | Multi-Family: cond 50%, func 50%, econ 100% |
| 16 King Street | 1-Story Frame: cond 60%, func 80%, econ 100% | 1-Story Frame: cond 50%, func 50%, econ 100% |
| 32 Orchard Street | 1-Story Frame: cond 80%, func 100%, econ 100% | 1-Story Frame: cond 80%, func 100%, econ 100% |
| 688 Crockett Ridge Road | 1-Story Frame: cond 90%, func 100%, econ 100% | Enclosed Porch (EP): cond 90%, func 100%, econ 100% |
Economic (external) obsolescence: the standard and the 2026 cards
“PT103” is Valuation of Real Estate, Maine Revenue Services assessor-training course (Chapter 4, The Cost Approach). “IAAO” is the International Association of Assessing Officers. Page numbers are the manual’s printed page numbers. Norway figures are counts of building rows on the 2026 property record cards, shown for the September 24 capture and for the committed roll. This page describes; it does not say what any owner should do, and it is not legal advice or an appraisal.
What PT103 says
- Definition (p. 65). “A loss of value due to external factors.” Examples given: the condition of other houses in the neighborhood and the presence of commercial property in an area that was once residential only. It is calculated after depreciation and functional obsolescence.
- Causes (pp. 83–85). Loss arising from causes external to the property, which the owner cannot control: oversupply of equally desirable properties; changes in the character of neighboring properties, such as rezoning for commercial or industrial use (the closer, the greater the loss); a neighborhood’s collective lack of attention to maintenance; loss of a major employer; availability of services; accessibility and road condition; topography.
- Where it is applied (p. 84). The manual says external obsolescence “is usually reflected in the site value, and care should be taken not to apply an external obsolescence to the site value. External obsolescence should be applied to the improvements.”
- Card headings (p. 85). Neighborhood; accessibility; utilities; services; topography; other.
- Worked example (p. 65). A 5% external obsolescence for a retail store built down the street: $104,625 × 0.95 = $99,394, rounded to $99,400. The manual’s later example, an established neighborhood of similar-aged homes, has none.
- Summary (p. 85). It cannot be controlled or fixed by the owner and “often, it has a greater impact on value than other depreciation considerations.”
What the IAAO says
The IAAO Glossary describes external obsolescence as loss from poor location or radically diminished demand. The Standard on Mass Appraisal says an external-obsolescence factor applied at neighborhood or district level should come out of market analysis and be validated by ratio-study performance within each stratum.
Another published view (not the Maine manual)
Longhofer, “Land Values and External Obsolescence,” The Appraisal Journal (2021), argues that an external condition usually lowers the land’s value first, so a building factor on top of a market-based land value can count the same loss twice, and that the structure itself carries external obsolescence only where its current use is not the site’s highest and best use. This differs from PT103 p. 84, quoted above. It is included so readers can see both treatments; PT103 is the Maine assessor-training standard.
What Norway’s 2026 cards record
| Factor | Measure | Sept. 24 cards | Committed roll (Oct. 1) |
|---|---|---|---|
| Functional obsolescence | Building rows below 100% | 794 of 11,548 | 1,576 of 11,515 |
| Parcels with at least one | 281 | 674 | |
| Economic obsolescence | Building rows below 100% | 102 of 11,548 | 103 of 11,515 |
| Parcels with at least one | 78 | 78 |
Parcels with an economic markdown, by class — committed roll: Commercial / institutional / other: 65; Outbuilding only: 4; Multi-family: 4; Frame house, 2 storey or more: 3; Frame house, 1¾ storey: 1; Frame house, 1 storey: 1. September 24 cards: Commercial / institutional / other: 65; Outbuilding only: 5; Frame house, 2 storey or more: 3; Multi-family: 3; Frame house, 1¾ storey: 1; Frame house, 1 storey: 1.
Selected cards, side by side
| Parcel | Sept. 24 card (main building) | Committed roll (main building) |
|---|---|---|
| 8 King Street | Multi-Family: cond 75%, func 100%, econ 100% | Multi-Family: cond 75%, func 100%, econ 100% |
| 9 King Street | Multi-Family: cond 75%, func 100%, econ 100% | Multi-Family: cond 75%, func 100%, econ 100% |
| 12 King Street | Light Industrial: cond 75%, func 90%, econ 90% | Light Industrial: cond 65%, func 65%, econ 90% |
| 13 King Street | Multi-Family: cond 75%, func 100%, econ 100% | Multi-Family: cond 75%, func 100%, econ 100% |
| 14 King Street | Multi-Family: cond 60%, func 80%, econ 100% | Multi-Family: cond 50%, func 50%, econ 100% |
| 15 King Street | Multi-Family: cond 85%, func 100%, econ 100% | Multi-Family: cond 85%, func 100%, econ 100% |
| 16 King Street | 1-Story Frame: cond 60%, func 80%, econ 100% | 1-Story Frame: cond 50%, func 50%, econ 100% |
| 24 Paris Street | 1-Story Frame: cond 80%, func 100%, econ 100% | 1-Story Frame: cond 80%, func 100%, econ 100% |
Land values on the committed roll for the same King Street parcels: 8 King $57,984, 9 King $66,720, 12 King $71,920, 13 King $65,628, 14 King $75,123, 15 King $67,240, 16 King $87,156.
Exemptions, deferrals and abatements — and where to apply
All applications go through the Norway Town Office (assessing) unless noted; State forms are on the Maine Revenue Services property-tax pages. Deadlines are April 1 for exemptions and current-use programs, 185 days from commitment for abatements. Links open State or Town pages; if one has moved, start at maine.gov/revenue/taxes/property-tax.
| Program | Who qualifies | What it is worth | How to apply |
|---|---|---|---|
| Homestead exemption 36 M.R.S. §681–689 | Maine resident, owned a Maine homestead for 12 months, primary residence on April 1. A home in a revocable living trust or a mobile home in a park qualifies. | $25,000 off assessed value — $274 a year at 10.96 mils. One application; it stays on until you move. | File with your town clerk at the town office by April 1. State page and form |
| Veteran exemption 36 M.R.S. §653 | Veterans 62+, or receiving a disability pension, who served in a recognized period; un-remarried surviving spouses, minor children, and parents. Paraplegic veterans get a larger exemption for adapted housing. | $6,000 off assessed value — $66 a year; $50,000 for the adapted-housing exemption. | Form and discharge papers to the Town Office by April 1. State page and form |
| Blind exemption 36 M.R.S. §654 | Owner legally blind, with a doctor’s letter. | $4,000 off assessed value. | Form to the Town Office by April 1. State property-tax relief page |
| Abatement 36 M.R.S. §841(1) | Any owner whose assessment is wrong — too high, mis-carded, wrong unit count, wrong acreage, or above a recent sale of the property. | Correction of the assessment; refund of tax already paid on the excess. Errors can be corrected back three years. | Written application to the assessors within 185 days of commitment; 60 days for a decision, then 60 days to appeal. MRS Bulletin 10: Abatements & Appeals · application form (MRS property-tax forms) |
| Hardship (poverty) abatement 36 M.R.S. §841(2) | An owner who cannot pay because of poverty or infirmity. Primary residence. Decided by the municipal officers (the Select Board), who may hear it in private. | Abatement of part or all of the tax for the year, at the Board’s discretion; must be re-applied for each year. | Written application to the Select Board through the Town Office; the Town Office has the Town’s poverty-abatement form and the guidelines the Board uses. MRS Bulletin 10, section on §841(2) |
| State senior property tax deferral 36 M.R.S. ch. 908 | Homeowner 65 or older, or permanently disabled; income and liquid-asset limits set by the State (raised in 2024); primary residence. | The State pays the tax to the Town and takes a lien; the deferred tax plus interest is repaid when the home is sold or the owner dies. It postpones the bill; it does not forgive it. | Apply between January 1 and April 1 at the Town Office; the Town forwards it to the State. State deferral program page and application |
| Property Tax Fairness Credit 36 M.R.S. §5219-KK | Maine residents whose property tax (or rent) exceeds a set share of household income; larger credit for filers 65 and over. | A refundable credit on the Maine income-tax return — paid even if you owe no income tax. | Claim on Schedule PTFC/STFC with the Maine Form 1040ME. State page and schedule |
| Senior volunteer tax offset 36 M.R.S. §6232 (Municipal Property Tax Assistance) | Residents 60 and over, in a town that has adopted the program by ordinance. Volunteer hours for the Town are credited against the tax bill at the State minimum wage. | Up to the statutory cap per year (on the order of $1,000–$1,500; the ordinance sets the details). | Ask the Town Office whether Norway has adopted a §6232 program. If it has not, the Select Board can; the statute is the authority. Statute text |
| Current-use programs Tree Growth, Farmland, Open Space | Tree Growth: 10+ forested acres and a licensed forester’s management plan. Farmland: 5+ acres with $2,000 farm income. Open Space: land kept undeveloped (values scale with the revaluation; see any woodland parcel review). | Woodland at $294–$304 an acre instead of $1,455–$6,200; pasture at $525. A withdrawal penalty applies later. | Application to the Town Office by April 1 for the following year. State current-use pages and forms |
The Homestead Exemption is not always worth $25,000
The table above lists the Homestead Exemption at its full $25,000, because that is what it is worth on the 2026 roll. But $25,000 (36 M.R.S. §684) is the exemption’s value only in a town assessed at 100% of market value. Maine Revenue Services scales it down, one dollar for every one percentage point, by the town’s own certified ratio: a town assessed at 80% of market value only gets to subtract 80% of $25,000 — $20,000 — because the exemption has to track the same yardstick as the assessment it is subtracted from.
2023 (certified ratio 85%): $21,250 exemption × 14.70 mils = $312.38 a year
2024 (certified ratio 80%): $20,000 exemption × 17.82 mils = $356.40 a year
2026 (certified ratio 100%, this reval): $25,000 exemption × 10.96 mils = $274.00 a year
Norway’s own certified ratio ran 100% every year from 2009 through 2022 (see the Town-wide findings tab), then slipped to 85% in 2023 and 80% in 2024 as assessments fell behind a rising market. The 2026 revaluation resets that ratio to 100%, which is why every Homestead Exemption on the new cards reads exactly $25,000, with no exceptions across the 1,225 homesteaded accounts on the roll. That is a real restoration of about $5,000 in exemption value — a 25% increase from the $20,000 a homesteaded owner was actually receiving in 2024. It is not, however, a 25% improvement in what the exemption protects. Among the 889 homesteaded single-family homes on the roll, the median 2025 assessed value (land and building, before any exemption) was $201,571; the same homes’ median 2026 value is $372,601, up 85%. The exemption covered about 9.9% of a typical homesteaded home’s value in 2025; fully restored, it covers about 6.7% of that same home’s much larger 2026 value. The dollar exemption went up by a quarter; the value it is measured against went up by five-sixths. That gap — not any change in the exemption itself — is why a homesteaded owner can receive the full $25,000 for the first time in years and still see a substantially larger bill.
Norway is not an outlier in this decline, and the exemption’s dollar value is about to move again for a different reason. Maine Revenue Services’ own county data show certified ratios falling across Oxford County between 2023 and 2024 — Waterford 70%→50%, Roxbury 86%→59%, Andover 90%→77%, Bethel 87%→77%, Peru 84%→69%, Sweden 80%→69%, Woodstock 80%→70% — against Norway’s comparatively mild 85%→80% slide; Norway’s own Municipal Valuation Return filings show this 2026 project as the town’s first professional revaluation since an in-house update effective April 1, 2007. Separately, the Legislature has already acted on the Homestead, Veteran and Blind exemptions themselves: P.L. 2025, c. 650, Pt. M (L.D. 2212) sunsets all three and replaces them with a single new statutory exemption, effective for tax years beginning April 1, 2027. Maine Revenue Services has not yet published guidance on what will count as an “equivalent exemption” under the new law, so the dollar figure homesteaded, veteran and blind owners will see on their 2027 bill is not yet set; this page will be updated once MRS issues it.
A separate check: the State’s own valuation of Norway
Every year the State Tax Assessor certifies an independent “State Valuation” for every Maine municipality — an equalized estimate of just value used to apportion the county tax and state education and revenue-sharing funds — and files it with the Secretary of State under 36 M.R.S. §305(1). Norway’s 2026 State Valuation, certified January 14, 2026, is $939.1 million. The 2026 roll analyzed on this site (net taxable value $1,193,348,401) runs about 27% above that independent figure. The comparison is not conclusive on its own: the State Valuation is built from sales through 2024 and was filed before O’Donnell’s 2026 roll was committed, so it could not have used this revaluation’s own numbers. It is also worth knowing that this figure — not the town’s local roll — is what sets Norway’s state education funding and revenue sharing; a local revaluation does not by itself change what the town receives from the State. And Maine’s statutory 70% minimum-ratio floor does not automatically trigger a revaluation when a town falls below it — Norway’s slide to 80% in 2024 would not, on its own, have forced this project. Whether the 2026 roll sits meaningfully above the market its own sales describe will be testable once MRS certifies the 2027 State Valuation from post-revaluation sales.
Town of Norway: Town Office, 19 Danforth Street, Norway, ME 04268 · (207) 743-6651 · norwaymaine.com. Verify current forms, limits and deadlines with the Town Office or Maine Revenue Services; program terms are summarized from statute and change from year to year.
Properties that pay no tax
Maine exempts certain owners — government, religious, charitable, educational and similar institutions — from property tax under 36 M.R.S. §652. The town still carries these parcels on the roll and assesses a value for them; that value is then exempted in full, so no tax is billed. This is a full list of the parcels whose 2026 assessed value is entirely exempted: Search by owner, street or parcel below. This is a public-record list, not a judgment that any exemption is wrongly granted — the §652 categories are broad and most of these are routine (the Town itself, the water district, churches, fire and rescue, land trusts, group homes).
Public records, openly read
Norway Parcel Review is built entirely from records that Maine law makes public, and it exists for one reason: so that the people who pay the town’s taxes can see how their share was decided, check it against the same evidence the assessors had, and act on what they find. Honesty and transparency in taxation and in the conduct of local government are not a courtesy the Town extends; they are the law’s starting point.
What the statute says
- The policy of the State. Maine’s Freedom of Access Act opens with a declaration of public policy: public proceedings are to be conducted openly, and the records and actions of public bodies are to be open to public inspection, with the Act to be liberally construed and applied to promote that policy. 1 M.R.S. §401
- Assessing records are public records. A public record is any written or electronic matter received or prepared for use in connection with the transaction of public business, unless a specific statute makes it confidential. The property record cards, the valuation and commitment books, the tax maps, and the sales files prepared for a revaluation are prepared for the Town’s business of assessing and collecting taxes; they are public records. 1 M.R.S. §402(3)
- Every person may inspect them. Any person has the right to inspect and copy any public record during reasonable office hours. The right does not depend on owning the parcel, living in the town, or giving a reason; a request need not be in writing; a denial must be in writing, within five working days, stating the statutory basis, and may be appealed to the Superior Court. 1 M.R.S. §408-A, §409
- Who “the assessors” actually are. Under Maine law the assessors of a municipality that has not created a separate assessing board are its municipal officers — in Norway, the Select Board. John E. O’Donnell & Associates is a hired contractor, retained to carry out the valuation work as the assessors’ agent; it is not itself “the assessors,” and being a hired firm does not give it the assessors’ legal authority. Abatement applications are decided by the Select Board, not by the contractor, and the assessment record required below must remain in the Select Board’s possession at the municipal office — not with O’Donnell & Associates. 36 M.R.S. §703
- The assessment record must stay at the assessors’ office and be available to owners. The assessors are required to make a record of their assessment and of the invoice and valuation, to deposit that record or a copy of it in the assessors’ office before the taxes are committed, there to remain, and to make the entire assessing record for a taxable property available to its owner in a timely manner. In a town whose selectmen serve as assessors, the assessors’ office is the town office. 36 M.R.S. §711; §703
- The commitment is a public act. The assessors commit the completed tax list to the collector under their hands with a warrant; the list of every parcel, its valuation and its tax is the commitment book, a public record on deposit with the Town. 36 M.R.S. §709
- Equal assessment is a constitutional right. All taxes upon real estate are to be assessed equally according to the just value thereof. A resident cannot know whether that promise was kept without seeing the record of how it was applied to the neighbors. Maine Constitution, Art. IX, §8
- What is not public, and is not here. The statute keeps confidential a taxpayer’s own declarations and income-and-expense filings made to the assessor, hardship-abatement applications, and personal identifiers. None of those appear on this site. Everything on it comes from the cards, the rolls and the sales files the Town itself publishes or holds as public records. 36 M.R.S. §706-A; §841(2)
What this initiative stands for
That a tax bill should be explainable to the person who pays it. That the tables, schedules and judgments behind an assessment are part of the public record of how it was made, and that an assessment whose basis cannot be stated should not be committed. That the same evidence the assessors used — the cards, the prior rolls, the sales — should be in residents’ hands before the deadlines that govern their rights run out, not after. That the levy, the levy-neutral rate and the distribution of the burden by class should be published beside any mil rate the Town proposes. And that reading public records openly, and saying plainly what they show, is not an attack on the Town; it is what the Freedom of Access Act says the Town’s business is supposed to look like.
Statutes summarized from the Maine Revised Statutes as published by the Legislature (legislature.maine.gov/statutes). Consult the current text before relying on any provision.
How to act, in order
- Before the list is committed, the assessors can correct any value informally on request. Ask in writing; keep the copy.
- After commitment, file a written abatement application with the assessors within 185 days (36 M.R.S. §841). If they do not answer in 60 days it is deemed denied; appeal to the Board of Assessment Review or County Commissioners within 60 days of denial; a further appeal goes to Superior Court within 30 days.
- Your record. Under 36 M.R.S. §711 the Town must make the entire assessing record for your parcel available to you; under 1 M.R.S. §408-A anyone may inspect any card.
- Kinds of records the Town’s own process refers to: purchase prices, sales of similar property (the study’s sales are listed on each review), a bill of sale for a mobile home, a woodland management plan.
- Exemptions and programs: see Relief that exists now above for each program, who qualifies, what it is worth, and the link to apply.
Where these figures come from
This site is produced from an analysis of the 2026 property record cards prepared by John E. O’Donnell & Associates for the Town of Norway’s revaluation, as published before commitment, and the Town of Norway’s municipal tax commitments from previous years (the 2022 and 2025 committed rolls, with each parcel’s land, building, exemption and tax as billed), contrasted against the available sales data from the Maine Multiple Listing Service (MLS) and sale prices and dates recorded on the Town’s 2021–2026 property record cards. The time adjustment, the screen for a usable arm’s-length sale, and the outlier trim applied to build a ratio sample from those sales are this site’s own analysis, not a Town-produced study — see “This site’s own test” under Town-wide findings for the exact method.
- 2026 assessments, land lines, building rows, grades, conditions, obsolescence factors, site charges, exemptions and visit codes — the 2026 property record cards, jeodonnell.com/cama/norway, as captured in September 2026.
- 2025 and 2022 values and taxes — the Town of Norway’s committed tax rolls for those years; 2025 tax is the amount actually billed at 20.38 mils.
- 2026 tax — computed at the proposed 10.96 mils with the exemptions shown on each 2026 card. If the Board sets a different rate the dollar figures scale accordingly.
- Sales, time adjustments and ratios — sale prices and dates recorded on the Town’s 2023–2026 and 2021–2022 property record cards; the time adjustment (3.37%/yr, fitted from this same data), the arm’s-length screen (single-parcel, $25,000 or more, sold 2023 or later) and the outlier trim (a 1.5×IQR band, 0.339–2.124, around the sales’ own ratio spread) are this site’s own analysis, not the Town’s; Maine MLS records for listing history and market medians where cited on individual reviews.
- Levy, mil rate and 2026 budget figures — the 2022 and 2025 commitments and the figures stated by the assessors’ agent at the September 1, 2026 hearing.
- Law and standards — Title 36 and Title 1 of the Maine Revised Statutes as cited; the IAAO Standard on Mass Appraisal of Real Property and IAAO Glossary; Maine Revenue Services bulletins and program pages linked above.
Prepared by a Norway property owner and published at norwayparcelreview.org. Assessment data are public records; every figure on this site can be checked against the published cards and rolls. Nothing here is an appraisal, a legal opinion, or advice from the Town or its assessors.
Budget trend line graph
Sixteen years of Norway’s town-wide property tax levy — the total amount raised by property taxes each year, before any single parcel’s share is decided — stitched from the state’s own certified record and the Town’s own figures for the two years the state has not yet published. The line is solid where a figure is certified (2009–2024) and dashed where it is the Town’s actual 2025 commitment or its proposed, not-yet-committed 2026 budget.

Source: Maine Revenue Services, Municipal Valuation Return Statistical Summary Reports (2009–2024); Town of Norway actual committed levy (2025) and proposed budget (2026). MRS’s certified 2022 figure ($7.59M) runs about 1.5% above the $7.48M figure used elsewhere on this site for that year — two source records for the same year. See The budget: what the Town raises, and where it is heading above for the levy math behind the 2026 figure and a year-by-year table.
Winners and losers of the 2026 reval
Set against the 2025 roll at the proposed 10.96 mils, 1,002 of the 3,365 taxable accounts with a billed 2025 tax of $250 or more end up paying less in 2026 and 2,363 end up paying more. The two totals are not close: for every dollar of relief the revaluation handed out, it asked for almost four dollars more from someone else.
The single biggest winner and the single biggest loser, in dollars
Ranked by percentage change, the extremes are small accounts where a tiny dollar swing produces a huge percentage. Ranked by the dollars actually at stake, two accounts stand apart from everyone else on the roll — one utility corridor and one mobile home park, moving in opposite directions by six figures.
| Parcel | Owner | Class | 2025 tax billed | 2026 tax (proposed) | Dollar change |
|---|---|---|---|---|---|
| 032-CMP-DIS | Central Maine Power | Utility corridor (carded as vacant land) | $314,661 | $243,647 | −$71,013 |
| 001-005 | Sun Town & Country LLC (Town & Country Mobile Home Park) | Commercial / institutional / other | $58,894 | $153,227 | +$94,333 |
CMP’s transmission and distribution corridor account carries no single owner-occupant to object to a $71,013 reduction; Town & Country’s park — one account behind several hundred mobile home lots — absorbs a $94,333 increase with no single homeowner positioned to challenge it either, since the individual lot rents, not this parcel’s card, are what residents actually see. Both figures are the parcel’s own 2025 billed tax against its 2026 tax at the proposed 10.96 mils with 2026 exemptions; neither account’s change is explained elsewhere on this site by a documented sale, so both are here simply because no other single account on the 3,514-parcel roll moved anywhere close to as many dollars in either direction.
What the tax bill actually did on the water
Waterfront land carries the steepest value increases of any land type in town — land alone on the 494 shorefront parcels identified on this site rose 152.7% from the 2025 roll to the 2026 cards, and these parcels’ total assessed value rose 125.0%. It is tempting to read that straight into the tax bill, but the mil rate falling from 20.38 to 10.96 absorbs most of a value increase before it reaches anyone’s bill, waterfront included. The chart below is the fairer comparison: what these parcels actually pay in 2026 against what they paid in 2025, set beside the same value-increase measure used for other property classes on this site.

Across the 494 shorefront parcels with a valid 2025 tax bill, taxes rose 21.4% in aggregate ($3,243,395 to $3,937,618, a total increase of $694,223) and 16.4% for the typical shorefront parcel — both above the townwide median tax change of +11.9%, but far short of the 125% value figure. 419 of the 494 shorefront parcels (84.8%) pay more in 2026; 75 pay less.
Waterfront parcels are those carrying a “Primary Lot” land row billed by linear water frontage on the property card (503 identified; 494 have a valid 2025 billed tax to compare against). Tax figures compare each parcel’s 2025 billed tax to its 2026 tax at the proposed 10.96 mils with 2026 exemptions. The property-class chart alongside it uses the same value-change measure (2025 land-plus-building value versus 2026 total value) detailed further in Tax by property class.
Why this exists, and how to help
Matthew Glatz is dedicating his own savings to create this aggregate data project of municipal tax records and expenses, collections and assessments from all available state and municipal public documents. If you’d like to support his LLM subscription used for data collection and calculation, or help him replace his tired, old socks before winter, send him a Venmo, or drop an apple crisp on his doorstep with a kind note.
Supplemental documents
Documents and charts produced by this project for public review, in the same order they were written. Each is a standalone file: the explainers are cited to the statutes, manual pages, and public records they draw on; the charts are tallied from the Town’s own published 2026 cards and commitment books. Nothing here is an appraisal, a filing, or legal advice. Parcel-specific assessment reviews are shared with the owners concerned and are not posted here. The one-page townwide analyses of condition, building grade, the site-improvement charge, and shed pricing are on the Articles tab.
The End of Maine’s Municipal Property Tax Levy Cap
What changed in state law in 2024 (L.D. 2102 / P.L. 2023, c. 603), why it matters in a revaluation year, the mil-rate mechanic, the unrealized-gain problem for legacy owners and family farms, who carries the risk, what the Select Board can do, and what residents can still do.
Open PDF · Download · Norway_Levy_Limit_Repeal_Explainer.pdf
Condition & Obsolescence: Industry Definitions
The appraisal profession’s own vocabulary for building condition and the two obsolescence factors — physical deterioration, functional obsolescence, economic (external) obsolescence — with IAAO, Appraisal Institute and Fannie Mae citations. Definitions only; no Norway data.
Condition ratings across the town
Where every one of the 11,552 building rows on the 2026 roll landed, against the Maine Assessment Manual benchmarks reproduced in PT103 (Excellent 90% · Good 80% · Average 70% · Fair 60% · Poor 50%). The roll’s median and most common rating is 85%; only 7.8% of rows sit at the State’s “Average.”
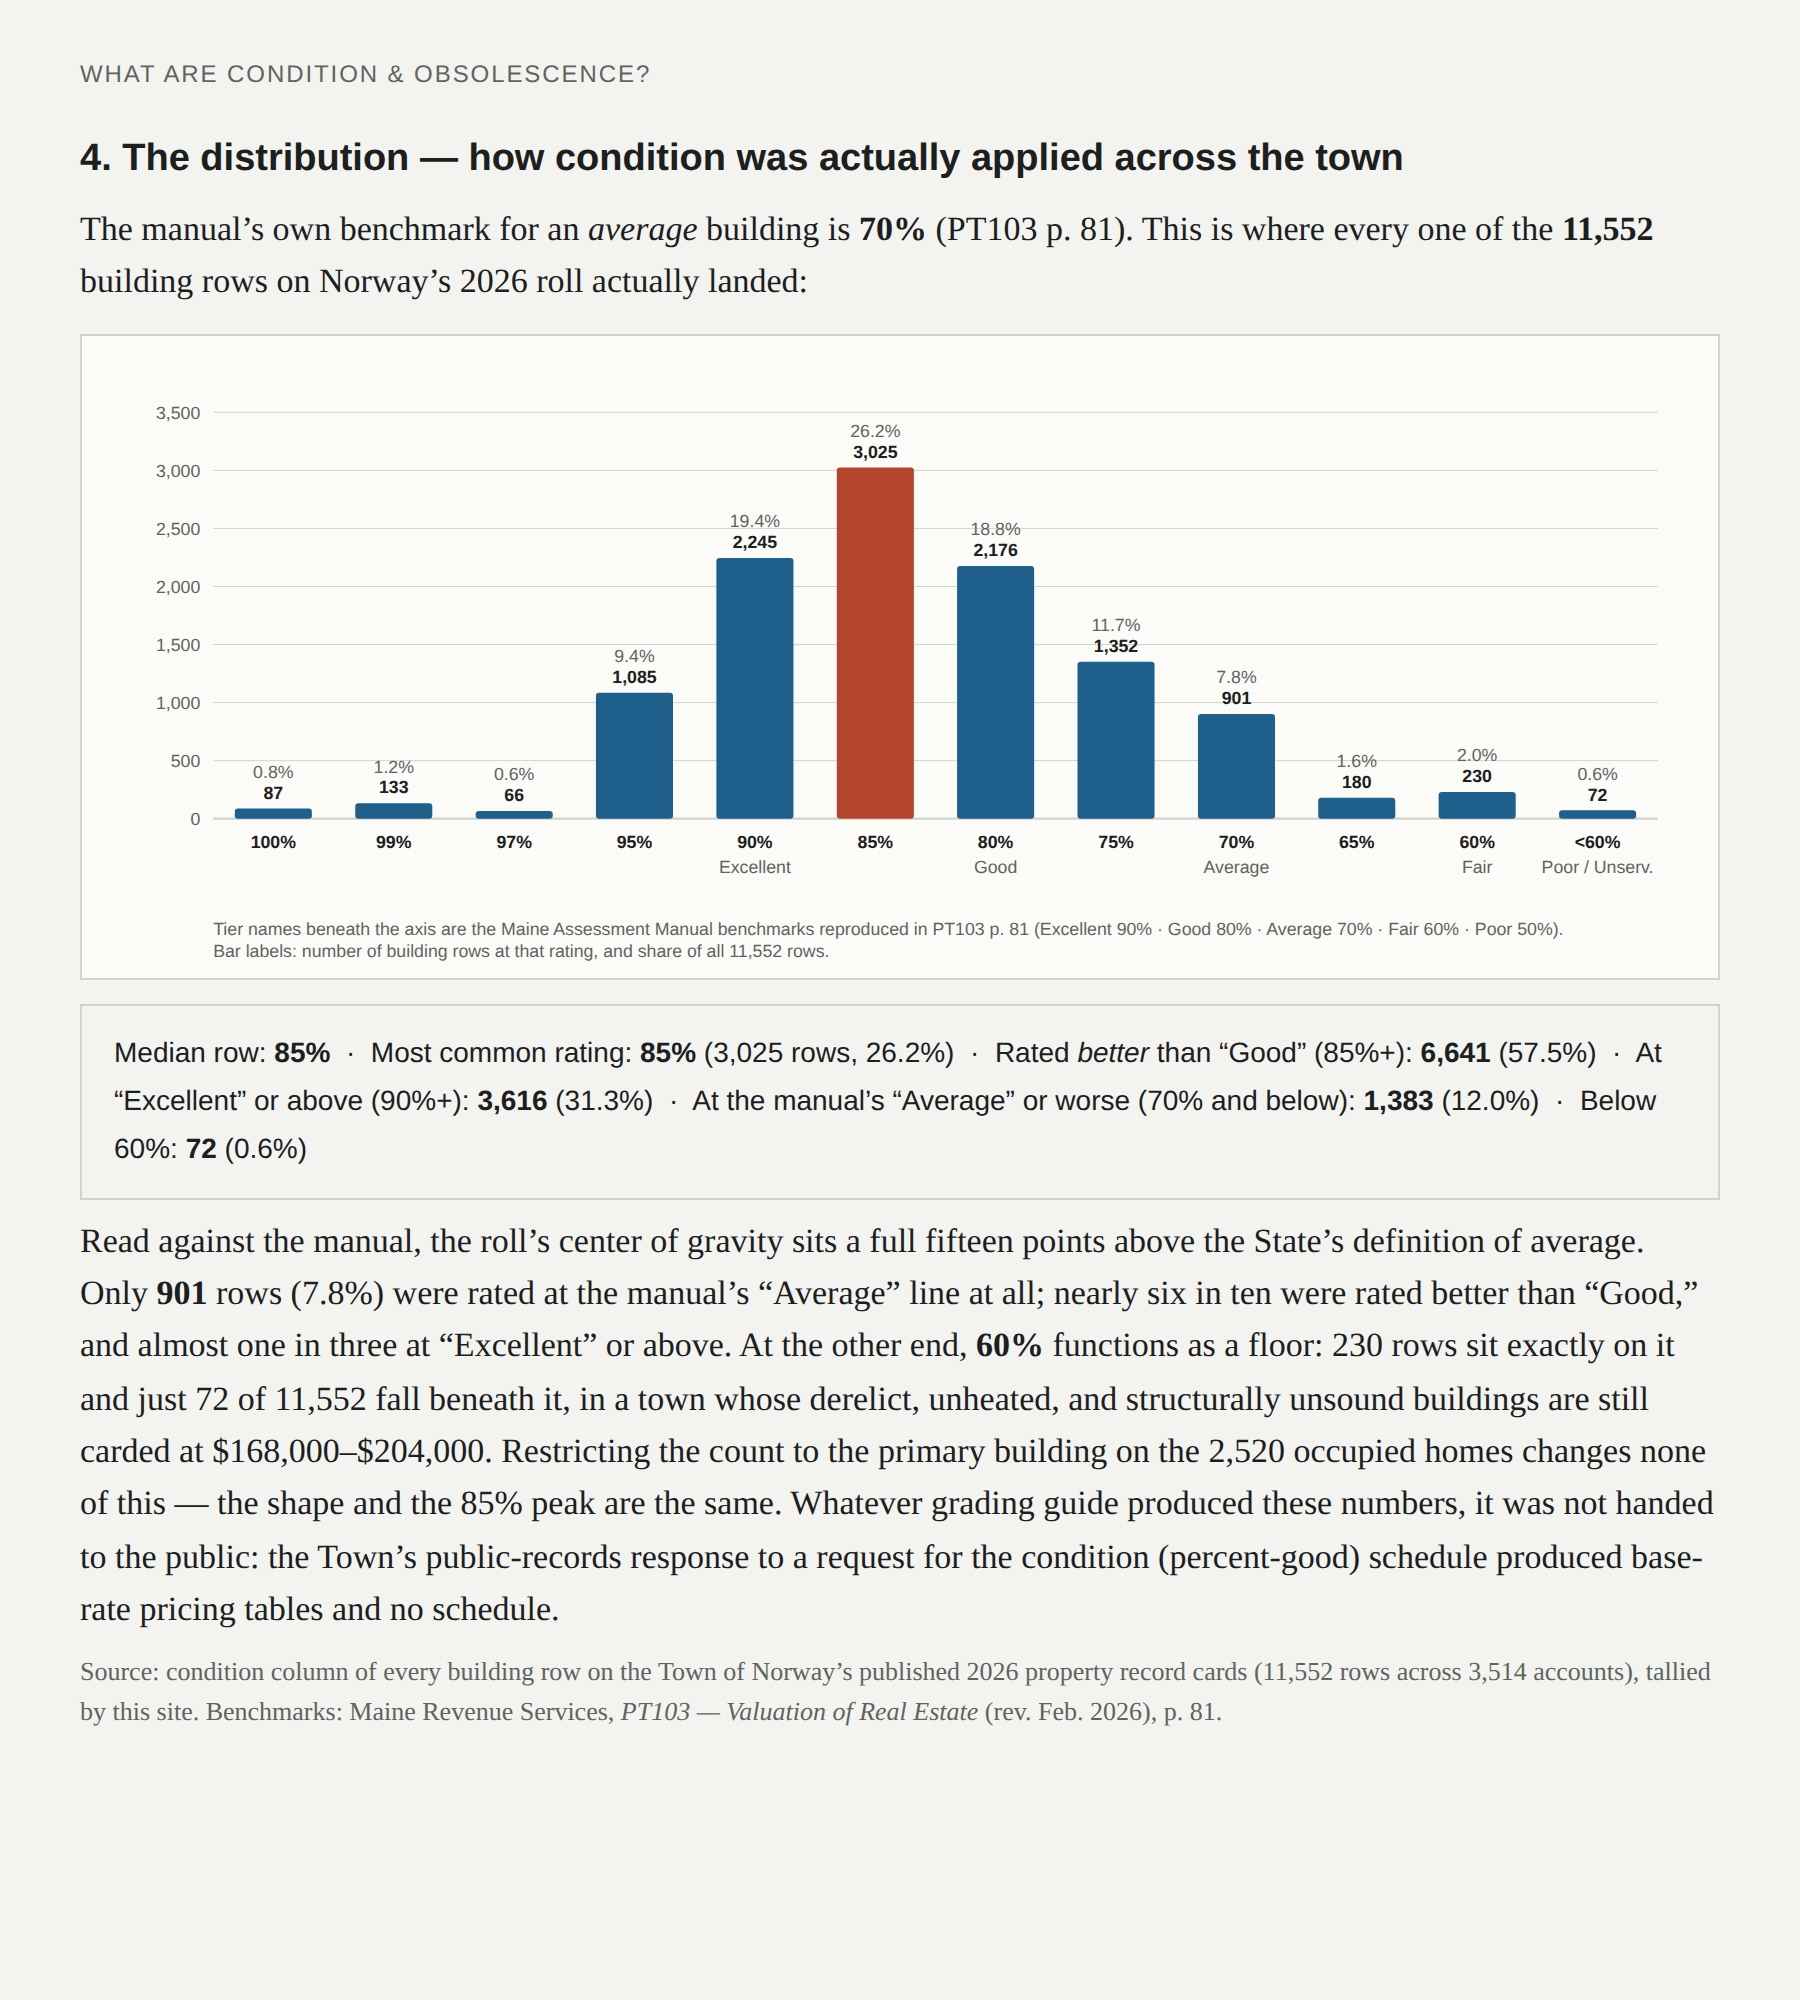
Open full size · Download · cond_dist_chart.png
Tax commitments, 2009–2026
Sixteen years of Norway tax commitments as a trend line, from the Town’s own commitment books.
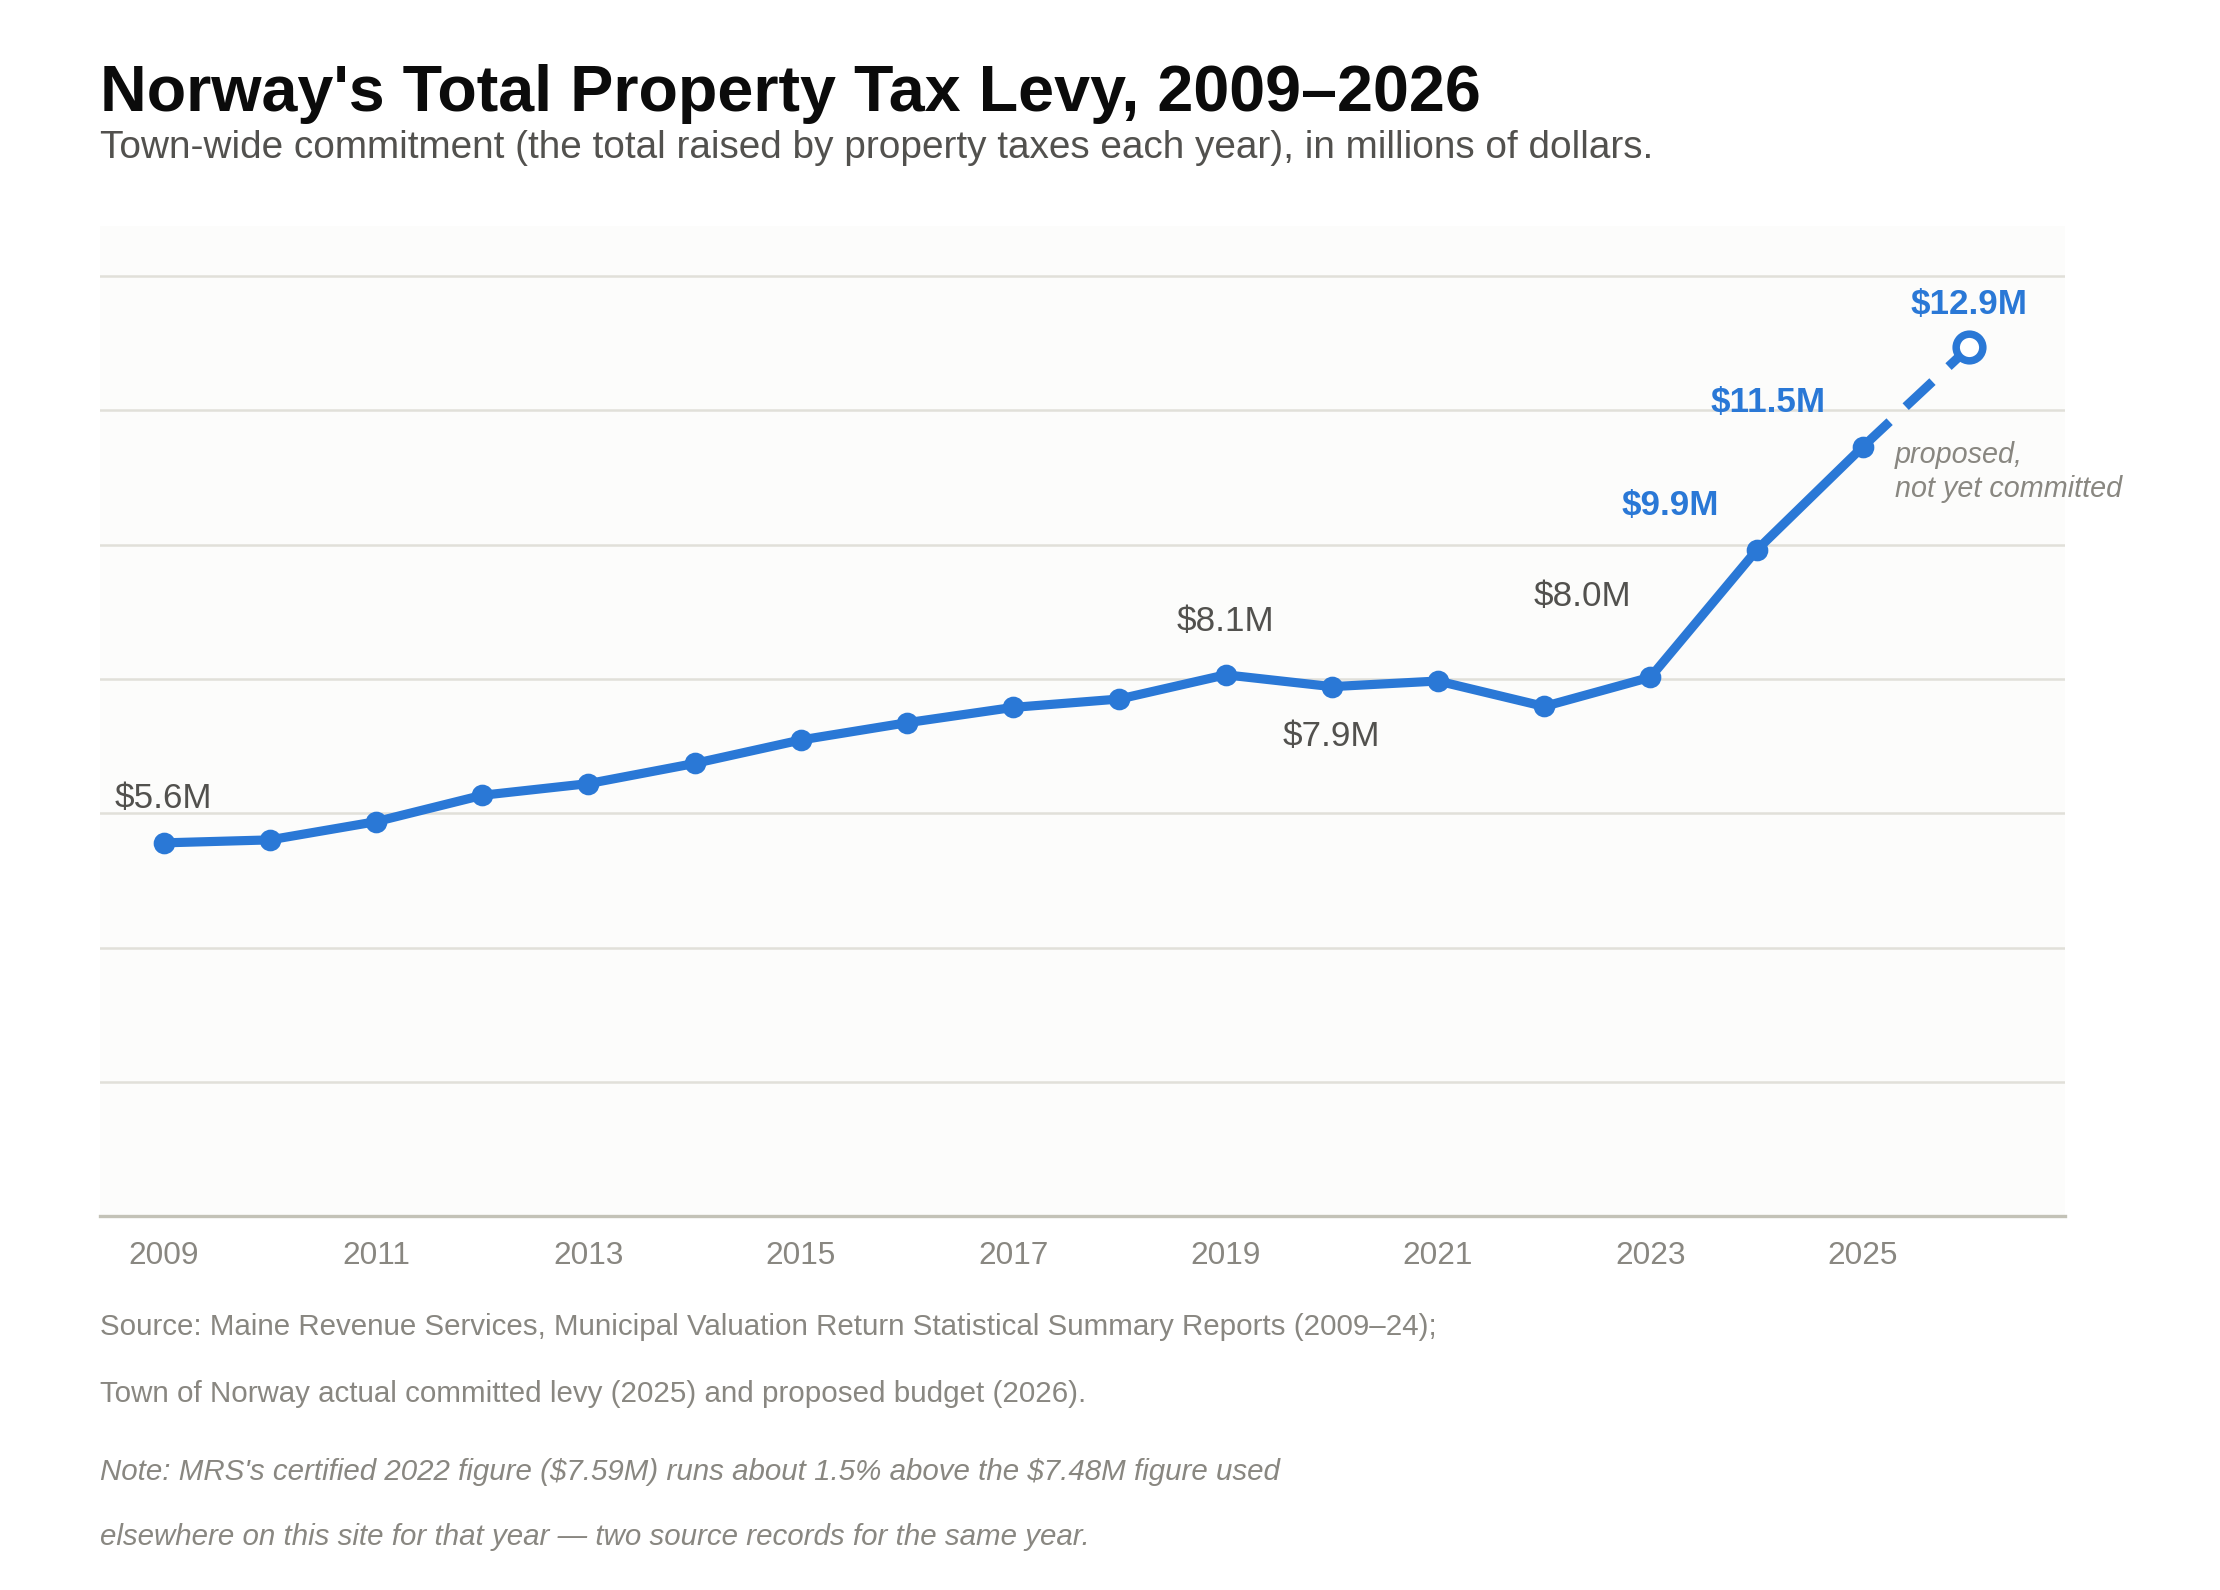
Open full size · Download · Norway_Budget_Trend_2009_2026.png
Land-table pricing, Tables 1–10
First-acre prices across the ten land tables used in the 2026 revaluation — the tables for which, per the Town’s public-records response, “no written definitions exist.”
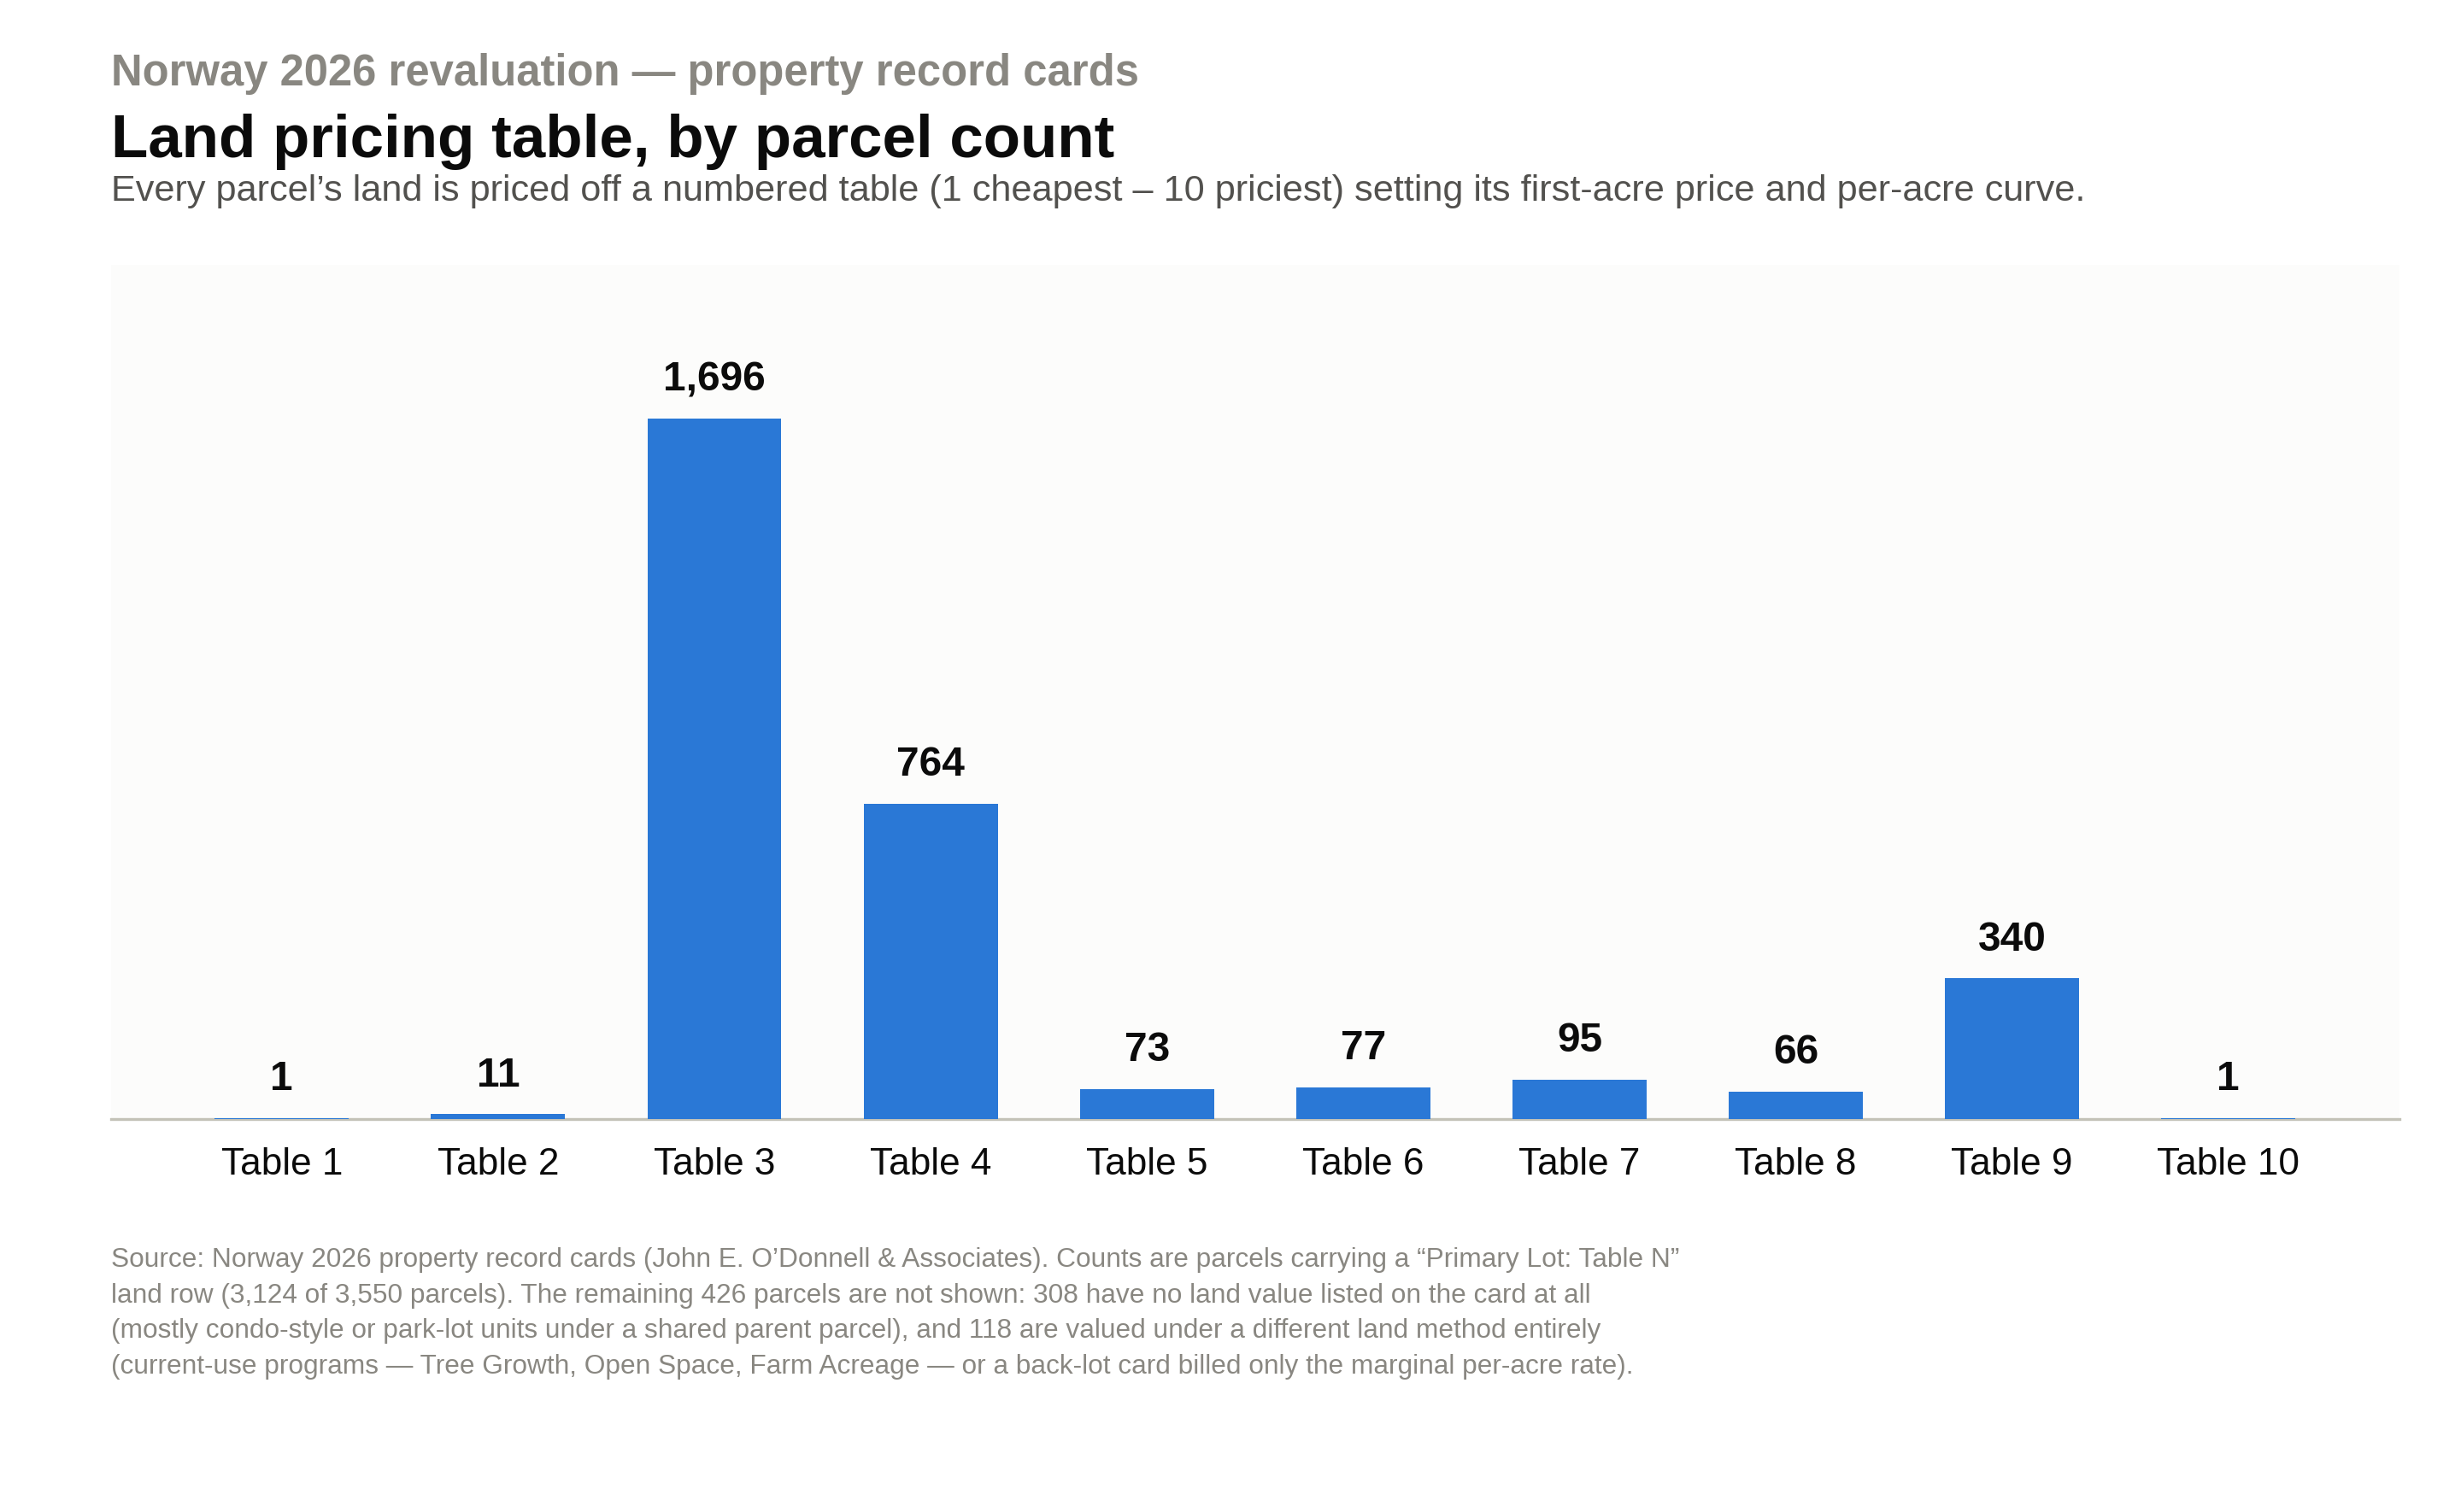
Open full size · Download · land_table_chart.png
Site-improvement grade schedule
The flat site-improvement charges by grade ($10,000 at Grade 1 to $300,000 at Grade 9) and how often each grade was applied on the 2026 roll.
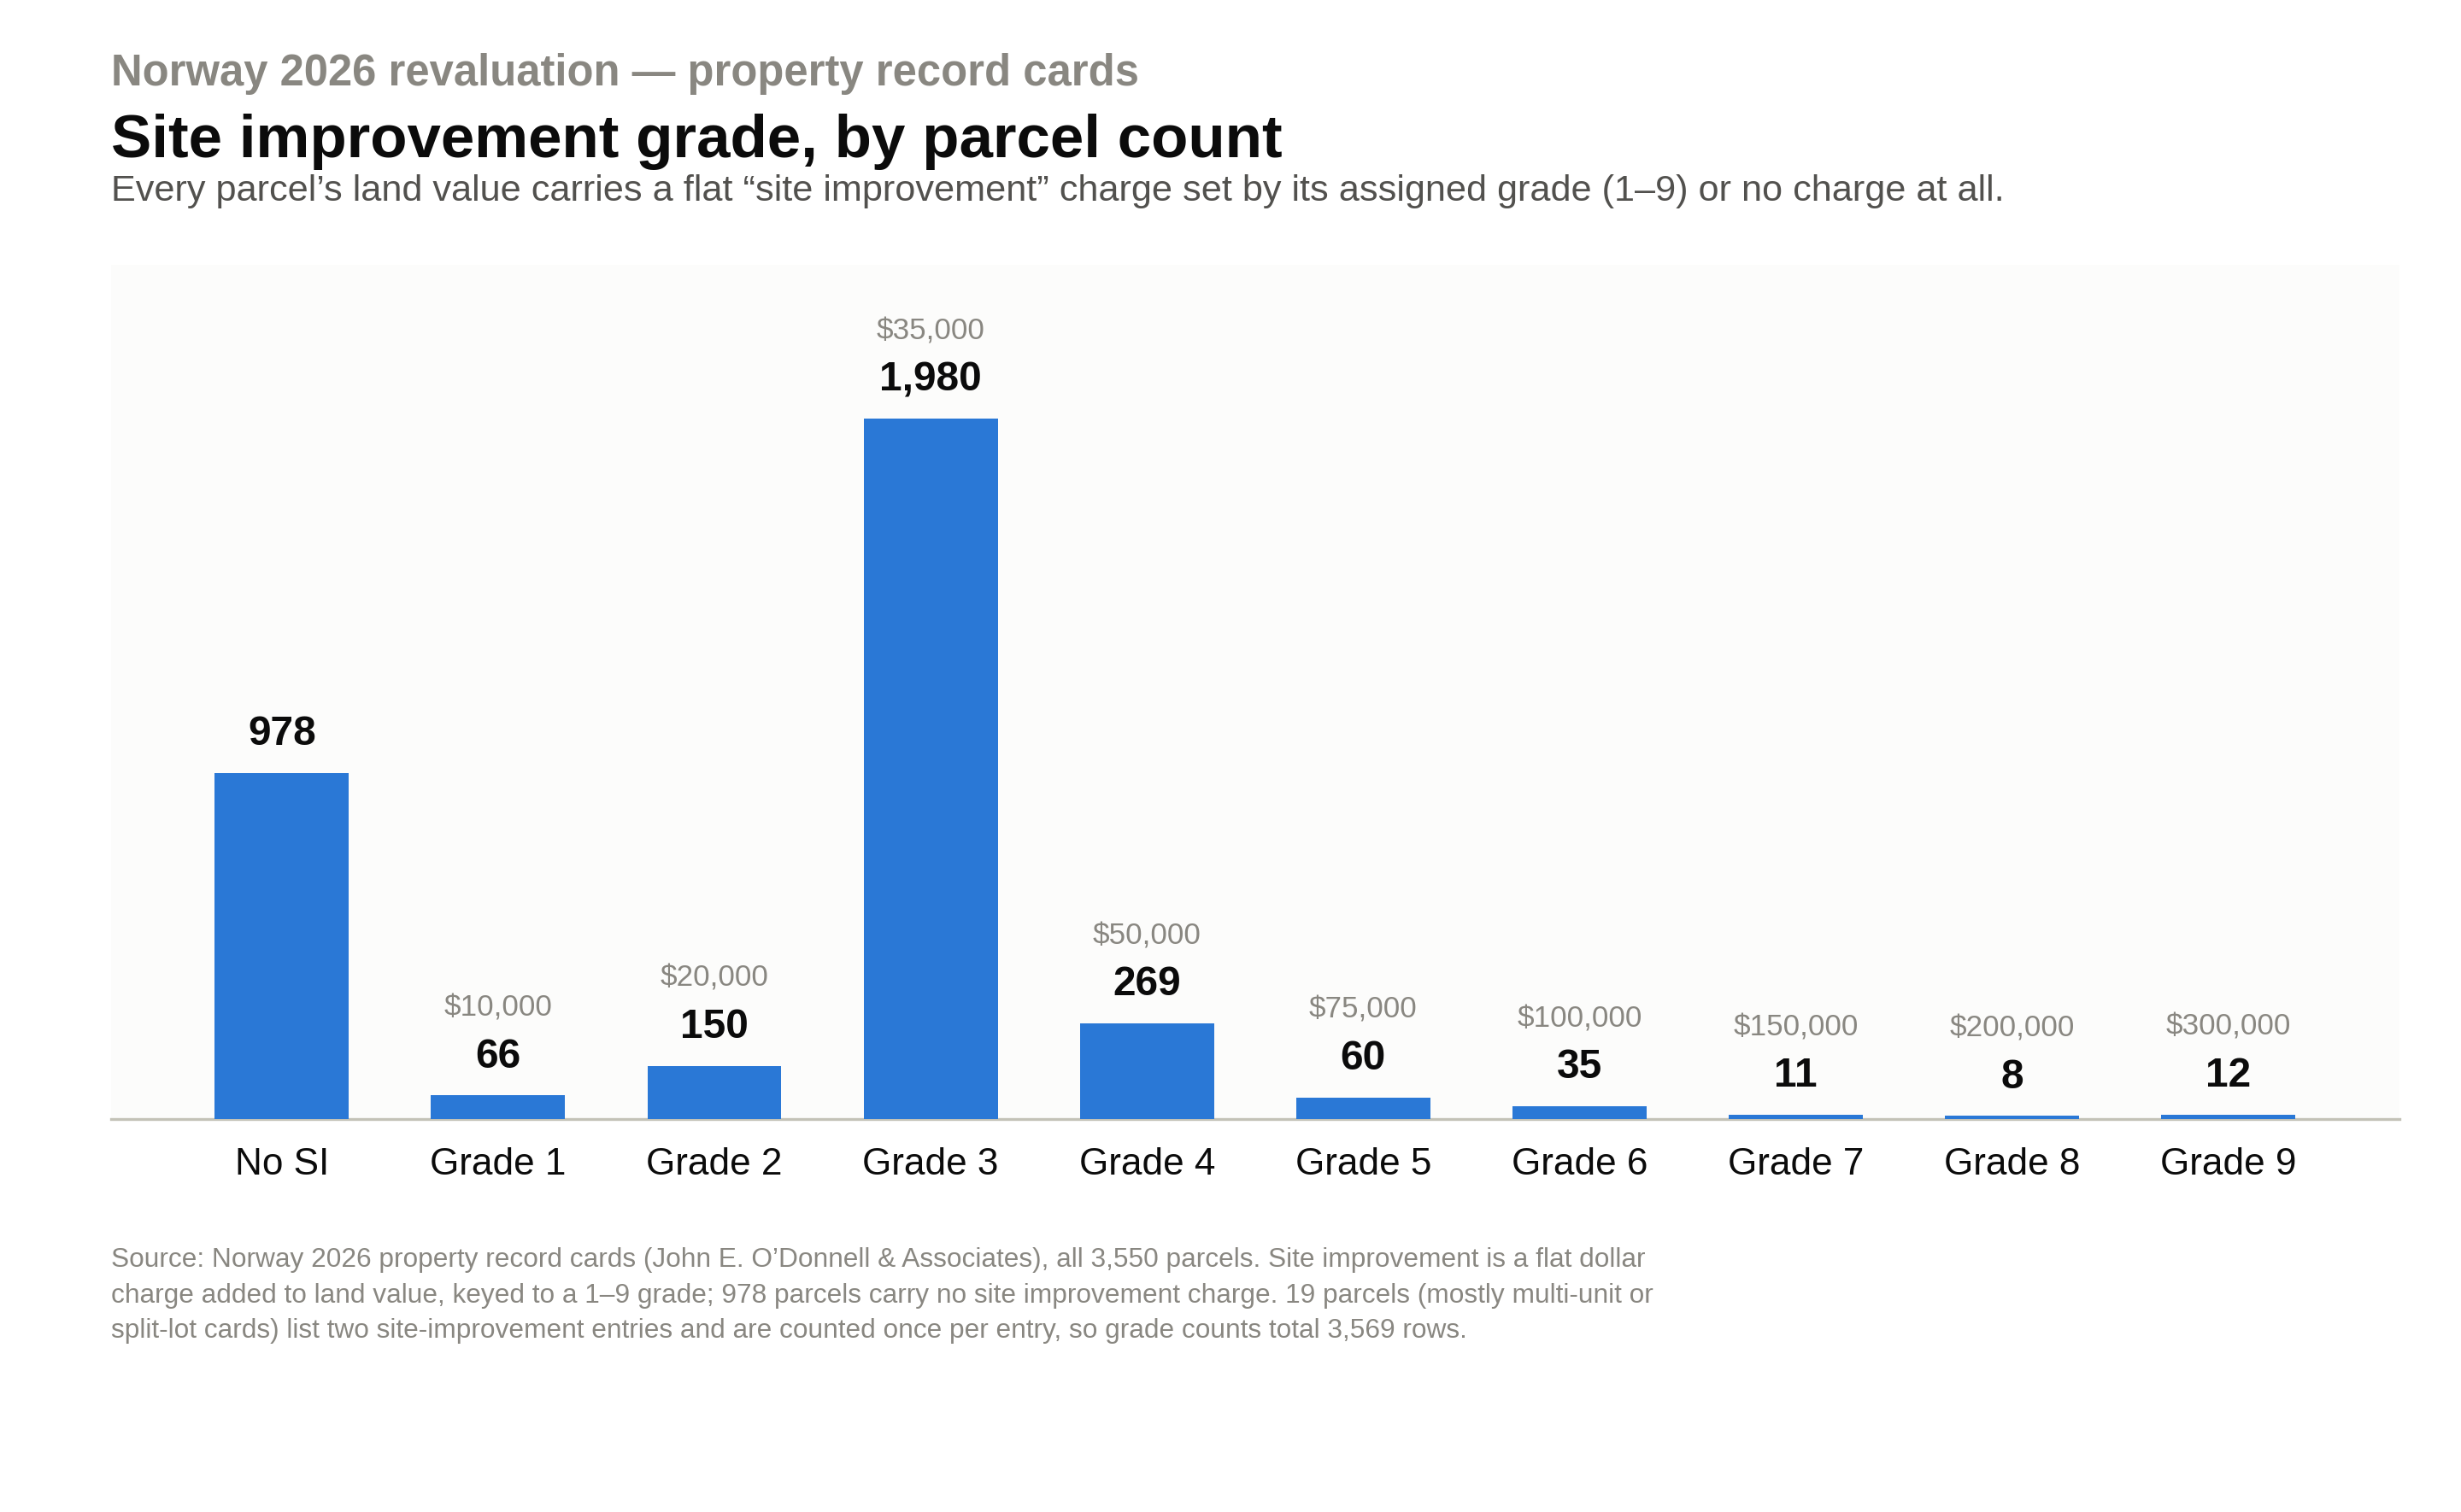
Open full size · Download · si_grade_chart.png
Building grade against age, 2026 cards vs the Town’s old cards
Grade is how well a house was built. On the 2026 cards the median grade never falls below 3.5 at any age. The Town’s own hand-kept cards carry older brick, stone and block-foundation houses at about 2.3 to 2.4 on the old scale; the 2026 cards put the same houses near 3.7. The firm has published no written definition of its 2.00–10.00 grade scale and no crosswalk to PT103’s five grade levels, so what any firm grade equals on the State’s scale is UNKNOWN. Note: this PDF draws a reference to PT103’s scale; that is the State’s scale, not a measured equivalent of the firm’s numbers.
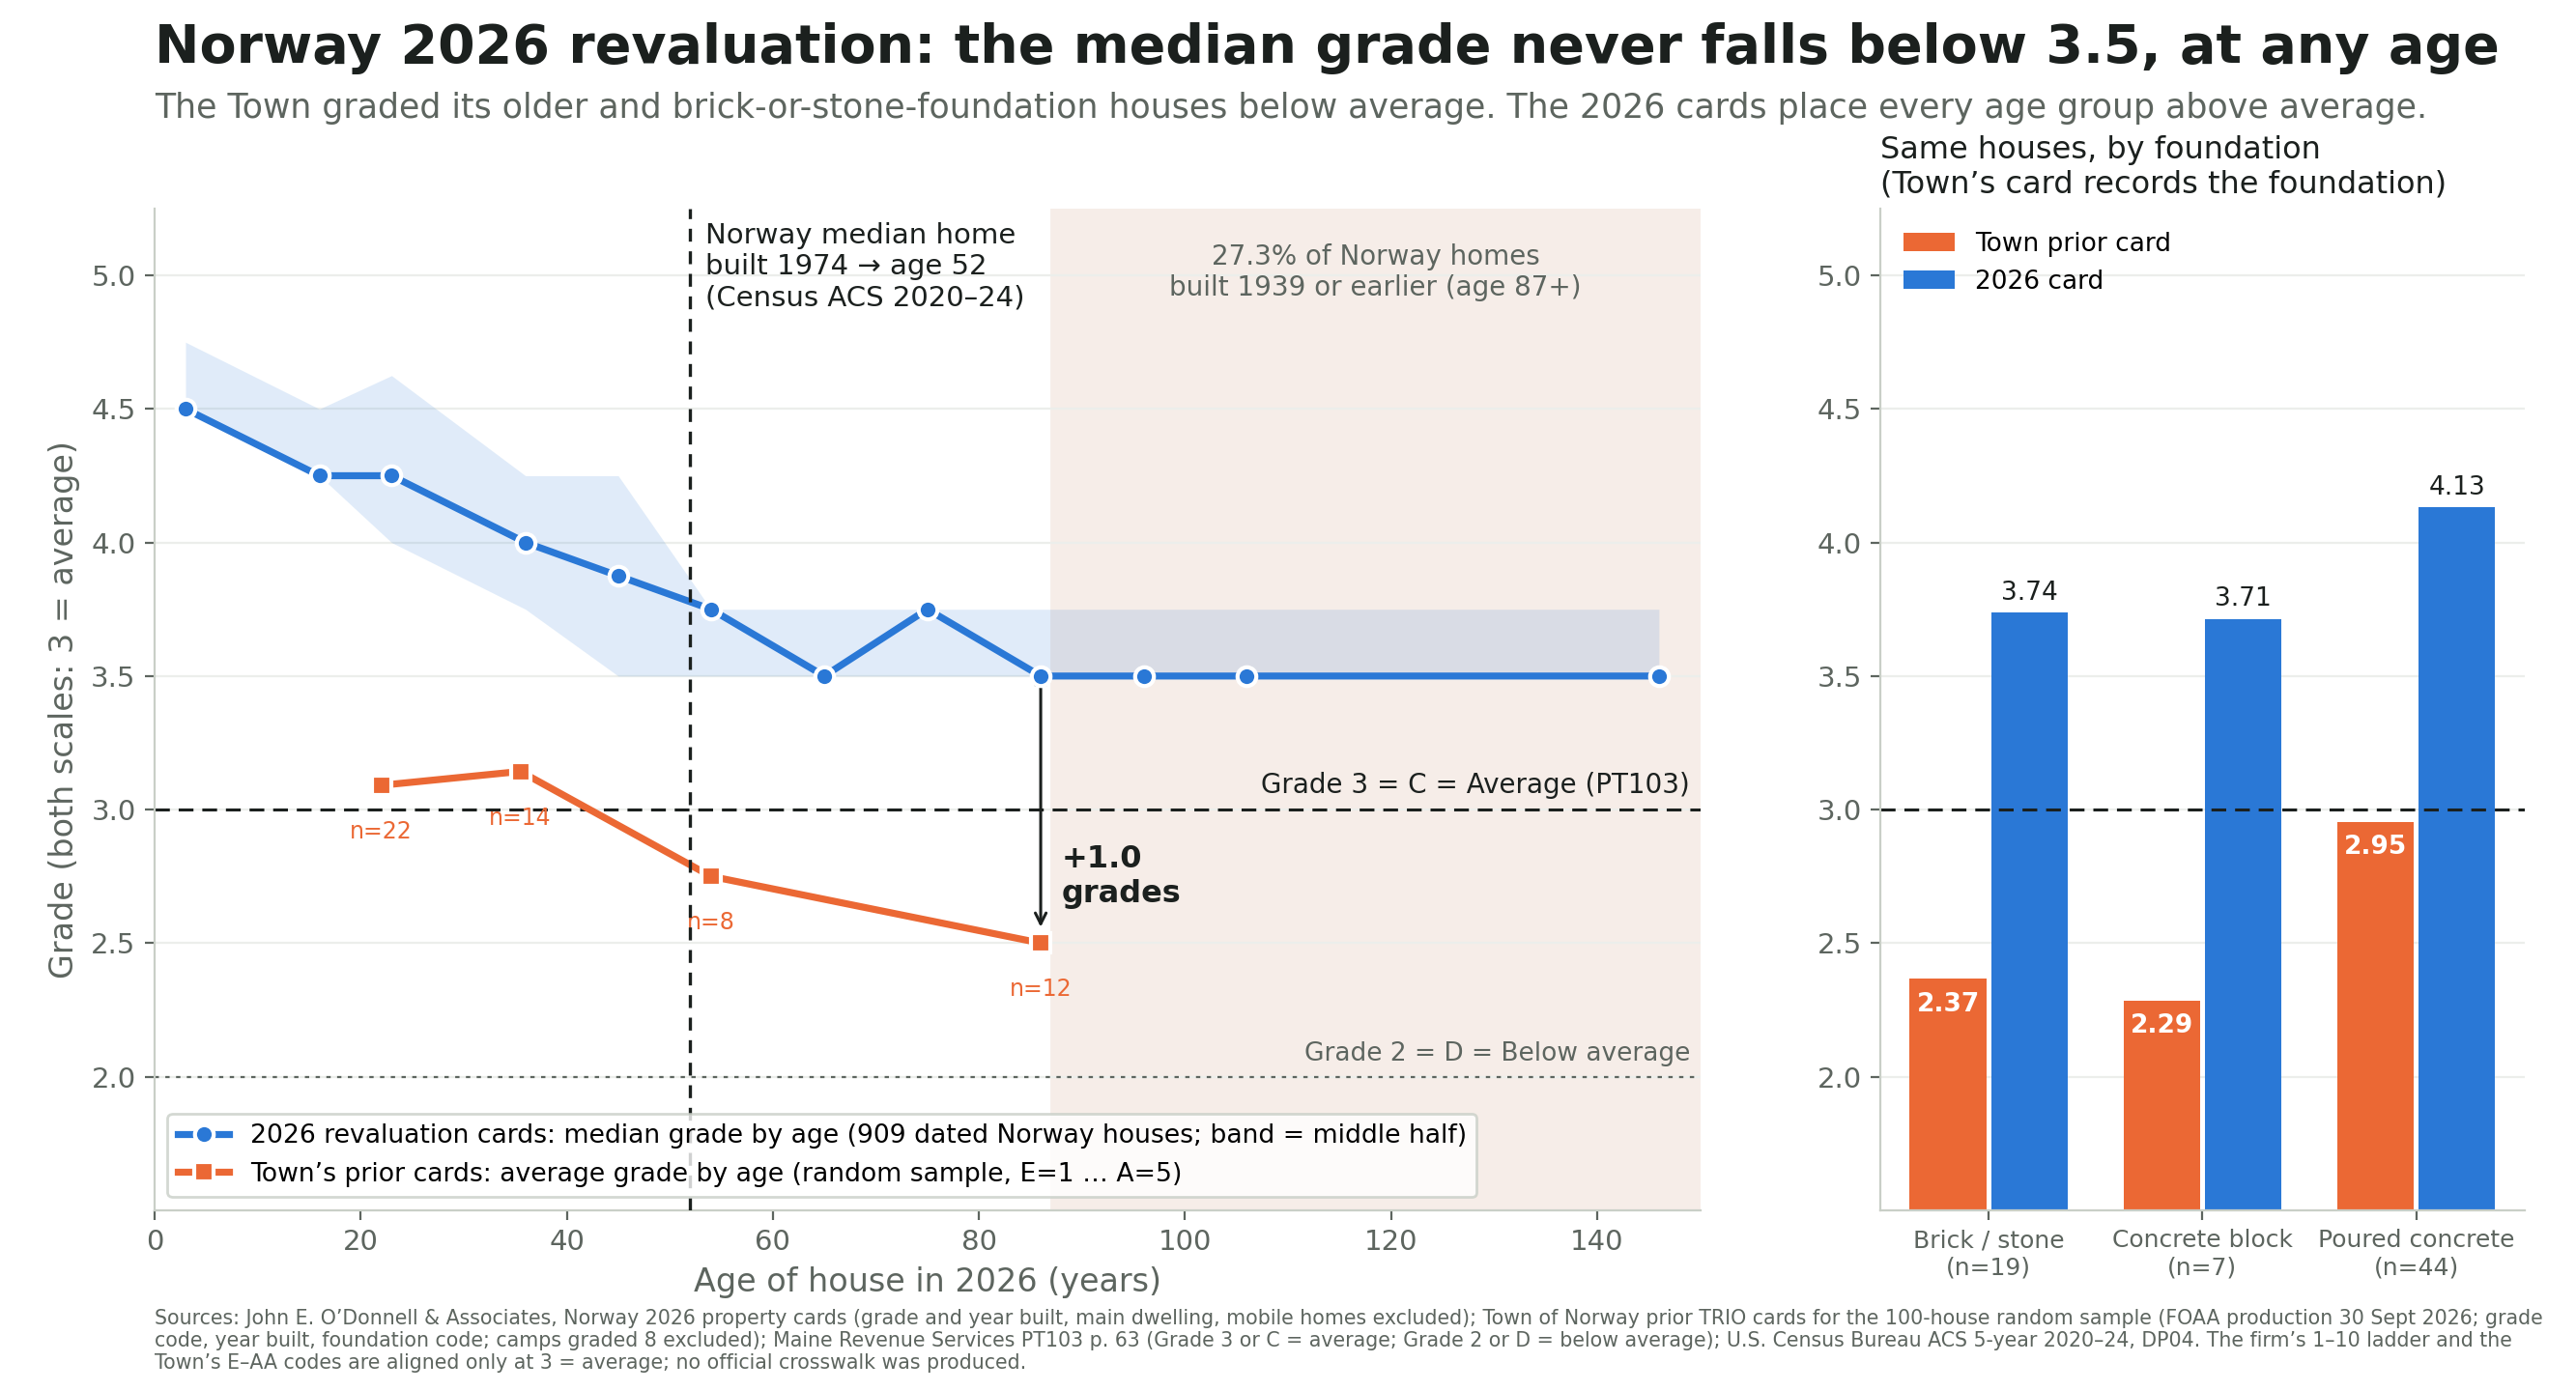
Open full size · Download · Norway_Grade_vs_Age_PT103.png
Condition against age, 2026 cards vs the State manual’s rate
Condition is how much value is left after wear. PT103 (p. 64) uses about one-half percent a year as its example: a 45-year-old house at 77.5%. On the 2026 cards condition falls for about forty years and then stops; houses older than that are held at 80–85% no matter their age, where the manual’s rate would put a 100-year-old house near 50%.
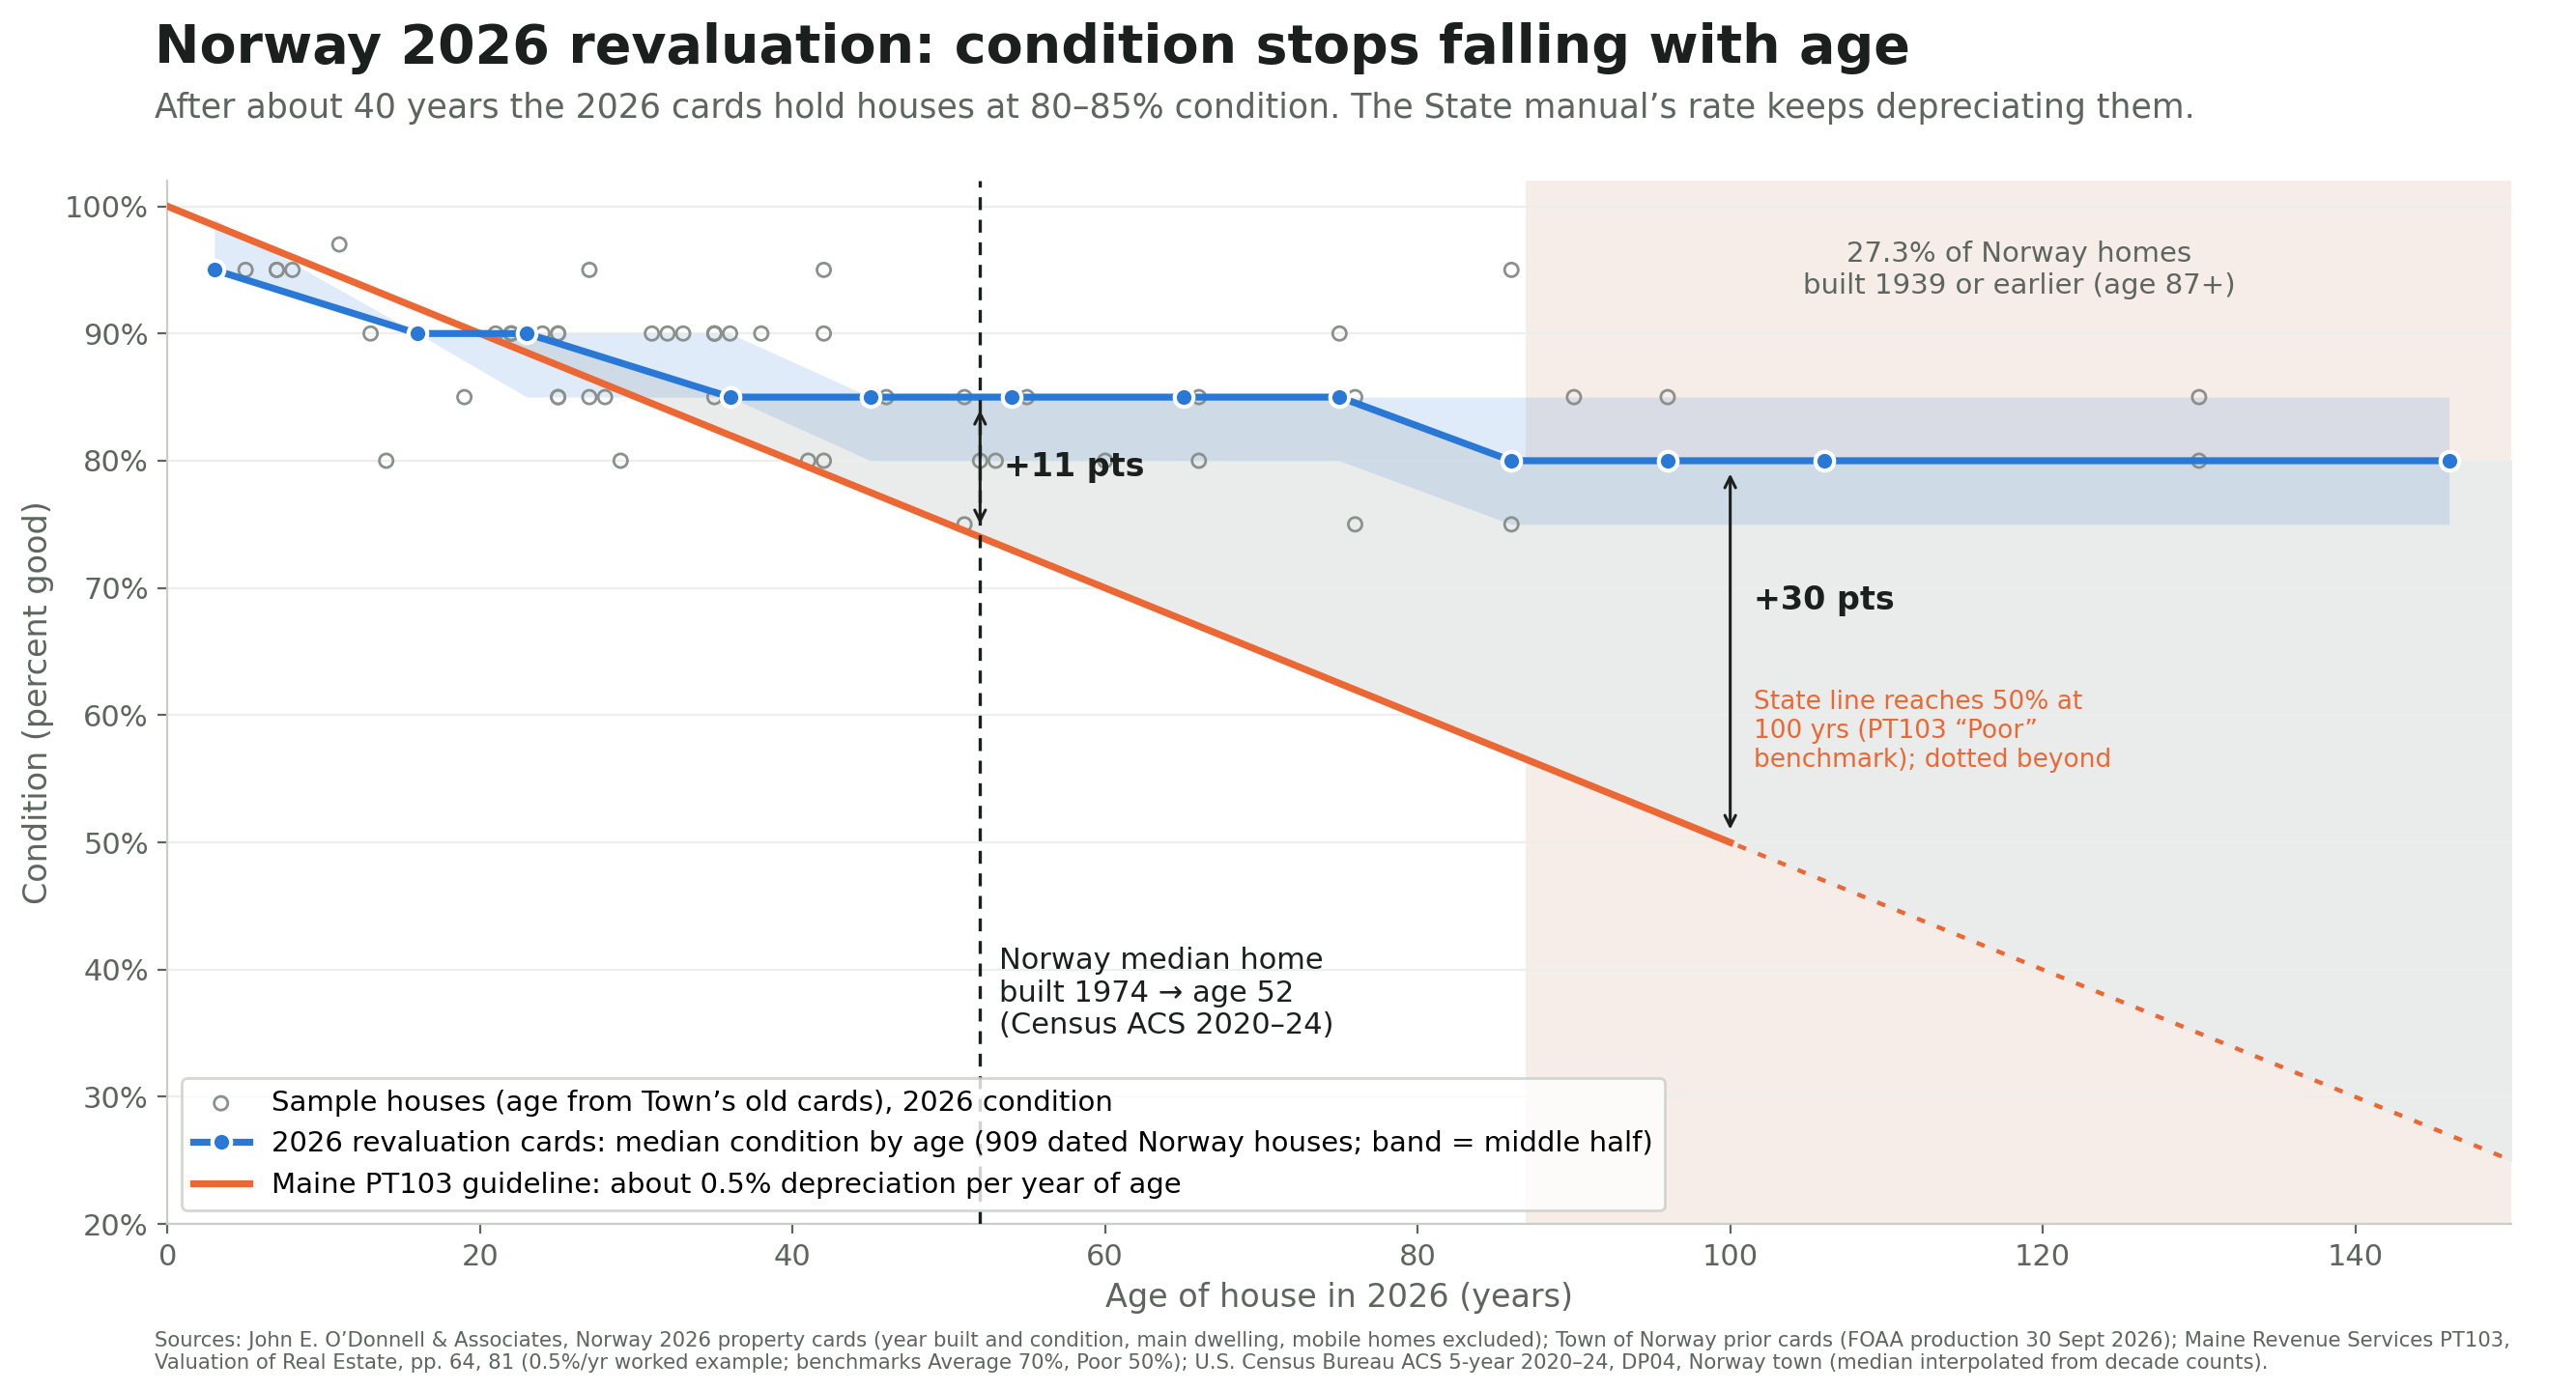
Open full size · Download · Norway_Condition_vs_Age_PT103.png
Every figure in these documents can be checked against the Town’s own card for the parcel in question and against the sources each document cites. Corrections are welcome through Leave your thoughts.
Add a historical parcel card
Historical parcel cards are public records. To add yours: ask the Code Enforcement Office or the Town Clerk for a copy of the parcel’s historical property record card (the Town charges $1.00 per copy), and drop the copy in my mailbox. Every card is a data point on what building quality, condition and construction in Norway looked like before the 2026 revaluation. Older cards for any parcel are welcome, not only your own.
Property record cards only, please. Do not include tax bills, identification, or anything that is not a parcel card.
Leave your thoughts
Recent submissions
Names, emails, and phone numbers are never shown here — only the map/lot and the message, exactly as people chose to make it public. Refresh
Loading…